
Micron Technology
-
you can't see what you don't want to see

Shipping 'now'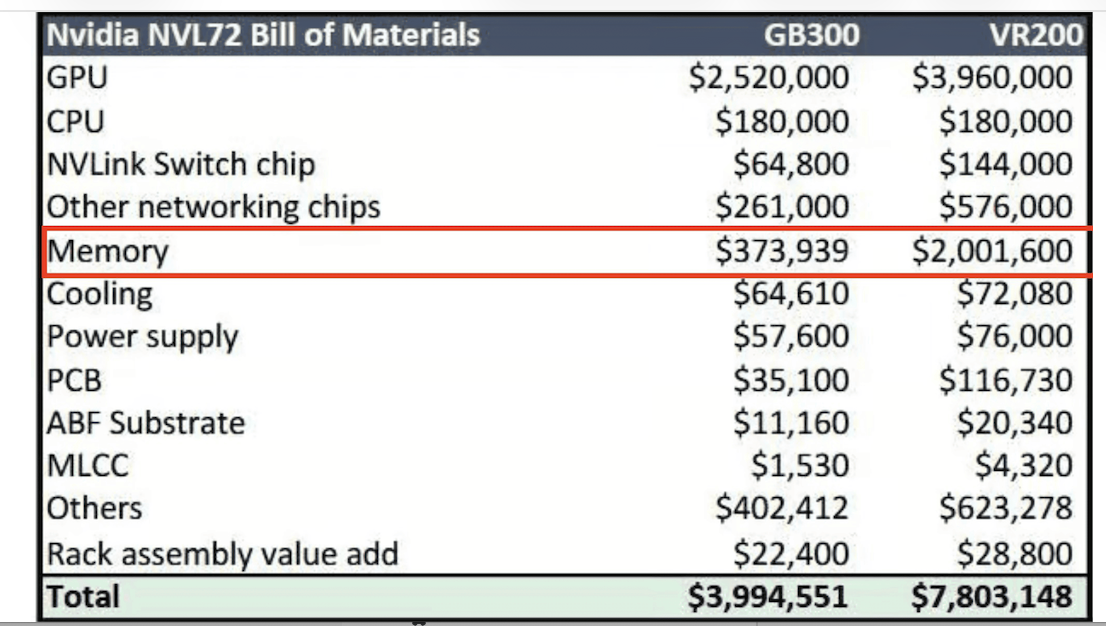
The guide was $50B revenue this quarter. I think their gross margin will be $50B
-
The US government has urged Apple to refrain from purchasing memory chips from Chinese suppliers. Commerce Secretary Howard Lutnick stated that the Trump administration is not in favour of American companies using Chinese memory, particularly from firms such as CXMT and YMTC, which appear on the Pentagon’s blacklist over alleged military links.
-
That’s good news..
Trump love him or hate puts his country first …
I don’t think our shower of shi.. would do the same -
I think it's somewhat moot what is decided at the Govt level as the Chinese vendors don't have any product to sell, and based on the evidence are asking a premium. Plus, the over supply argument has been put to bed, regardless of what certain vested interest will continue to promote.
We will have severe shortages for at least 5 years and possibly much more. A very very long time in this game-trying to predict markets in 5 years is pointless so ignore that too.
If anything the infection of physical AI is a matter of when not if. Cars will get to level 4 soon, robots will proliferate. Both will need material memory to allow real time (zero shot) inference. It's obvious, well at least to some.
We will discuss this in due course but the next phase in the memory road map is custom silicon where companies like SK/Micron are working with customers to produce bespoke silicon. We know they are working with Anthropic and Nvidia. Why it's a big deal. It makes their products not just commoditised, it means these co-designs are deeply embedded in their AI architecture which effectively locks out competitors.
-
Jensen Huang (NVIDIA founder and CEO) and Tim Cook (Apple CEO) both provided supportive statements in Micron’s August 20, 2026 announcement of Micron Research Labs (a U.S.-based long-horizon research institution headquartered in Boise, Idaho, backed by a planned $10 billion investment
Jensen Huang:
“Micron is taking on one of the great challenges of the AI era — reinventing memory technologies and architectures to fuel the next generation of increasingly powerful AI systems. By bringing together advanced manufacturing and the broader technology ecosystem, Micron is helping drive the breakthroughs that will define the next era of AI and computing.”and surprising, given the rift (restoring relations?)
Tim Cook:
"For more than two decades, Micron has been an important partner, providing memory technologies for Apple’s groundbreaking products that people love and use every day around the world. With the launch of Micron Research Labs, they are building on a legacy of leadership in semiconductor research to drive breakthroughs in memory and computing for decades to come. Apple believes deeply in American innovation, and we’re proud to support Micron as it expands leading-edge manufacturing and R&D in the United States.” -
Yesterday Aug 20),Micron Technology (MU) CEO Sanjay Mehrotra said AI has fundamentally changed the memory business, creating a more durable source of demand for an industry historically prone to boom-and-bust cycles.
“Today there is no AI without memory. AI systems need more memory. They need higher performance memory. They need lower power memory,” Mehrotra told Jim Cramer on “Mad Money.” “So, the value of memory, that equation has totally changed.”He added that data-centre customers currently want roughly 50% more supply than Micron can commit, underscoring the tightness in the memory market.Mehrotra also called memory “the strategic infrastructure of the AI era,” pointing to growing demand beyond data centres from autonomous vehicles, robots, and AI-enabled consumer devices.
“Without memory, you cannot make AI smarter or faster, without memory you can’t scale up AI. AI is advancing and a lot of content is getting generated. All of that content has to be stored, has to be processed through memory,” he added.How bullish this is / re-rating the company.
This is strongly bullish and supports a meaningful re-rating of Micron. Historically, memory (DRAM/NAND) has been a classic cyclical industry: sharp price collapses when supply outstrips demand, followed by recoveries. Investors therefore applied low valuation multiples reflecting that volatility and limited visibility. Mehrotra’s comments mark a clear structural shift. He frames AI as creating durable, multi-year demand that is no longer purely cyclical: AI systems require more, higher-performance and lower-power memory; data-centre customers already want ~50% more supply than Micron can currently commit (tight market conditions); and memory is positioned as “the strategic infrastructure of the AI era,” with demand also expanding into autonomous vehicles, robots and AI-enabled devices. In valuation terms this implies: Higher and more sustainable utilisation/pricing power.
Better earnings visibility and potentially elevated through-cycle margins.
A transition from “cyclical commodity” to “structural AI enabler.”Markets typically reward that shift with higher multiples (P/E, EV/EBITDA, etc.). If investors accept the durability thesis, Micron can re-rate from a traditional memory multiple toward something closer to other AI infrastructure names, supporting a higher share price even before further earnings upgrades.
-
Nvidia is shifting its primary HBM4 configuration from 12-high to 8-high stacks for the second half of the year, driven by thermal-management needs and supply-chain resilience.
Samsung and SK Hynix, previously focused on denser 12-high products for the Vera Rubin platform, are now increasing their 8-high share to meet Nvidia’s request.
Micron has been the only major supplier committed to 8-high HBM4 from the start.
This change validates Micron’s strategy, eliminates a potential competitive disadvantage, and positions it for stronger volume and share as Nvidia seeks a broader, more balanced mix of 8-high product across all three suppliers. The same preference is also emerging for next-gen HBM4E. In short, Nvidia just endorsed the path Micron was already on — clear product validation and a meaningful win for MU.
-
from nvidia earnings prepared notes-wow

rerating?
-
Micron share price is like a day trading one at the moment …
-
Micron share price is like a day trading one at the moment …
@Ducati996R said in Micron Technology:
Micron share price is like a day trading one at the moment …
Indeed - it's all over the place. I await some nice steady growth in the coming months but do wish it would get on with it ......
-
Micron 512GB DDR5 RDIMM
Micron has just demonstrated the world’s first 512GB DDR5 RDIMM, aimed squarely at next-generation AI/data-centre servers. It is a significant step up in memory density: one module holds 512GB, with speeds of up to 9,200 MT/s. Micron expects volume production in H2 2027. AMD and Intel are already validating it on future server platforms.The power saving is particularly striking. One 512GB module consumes approximately 16W, versus 44.2W for four 128GB modules providing the same capacity — a reduction of more than 60%.
The key fact to add is that Micron's memory opportunity isn't solely an AI/HBM story. The new 512GB DDR5 module targets the much broader non-AI data-centre/server market, while HBM4/HBM4E captures the AI accelerator market.
That gives MU two separate demand drivers. Even at $15k per module, you're looking at $360k of DRAM per server.
Validation of durability!
-
Whats your thoughts on the upcoming MU earnings @Adam-Kay ? MU is flying at the moment.
-
Hi,
Guidance was $50b and $31 EPS(say $32 billion net income). I expect a significant beat. The market expects $53B. I think it will be quite a bit more. $58, maybe as high at $60B (eps $35?). Will they guide $70b+ for Q1(fiscal 27). I don't know, nobody does. Just remember one simple fact, there is no peak in sight, they are constrained. Demand is increasing every quarter, every year for as far as they can see. Micron are now producing quarterly earnings only a few elites can match. More than Apple, as much as GOOG. 15X more than AMD (same valuation
 ) 1000X more than Crowdstrike
The question is, are their earnings durable-I think they. You dont have to maintain 90% margins to justify a higher valuation because the market has never valued them accordingly. My view is long term the company will be able to produce EPS as a base line in the range $200 with higher peaks before.I have no idea what the reaction will be-it's not priced accordingly(is it) so im only interested in the numbers and what management have to say
My thoughts are-everyone is talking about HBM, however HBM is actually very expensive to produce as it hoovers up a large wafer count vs the end bit yield and is actually a drag on margins. Inference re agentic Ai is making other Dram more important when it comes to margins.
The AI memory race is shifting beyond pure HBM market share towards CPU-attached memory, where margins look structurally stronger and Micron currently holds the advantage(over SK).
Agentic AI workloads require agents to maintain long-running state, plan and manage expanding KV caches. While model inference still runs on GPUs with HBM, much of the supporting work and context lives on the CPU side in system memory and storage.
This is pushing demand towards high-capacity, power-efficient LPDRAM in SOCAMM form factors, high-capacity server DDR5 RDIMMs and data-centre SSDs for offload. Nvidia’s own software already moves KV cache out of scarce HBM into these cheaper, higher-capacity tiers .In 2026 HBM pricing was largely locked in at lower levels from earlier negotiations, while conventional DRAM contract prices surged several-fold.
Because HBM also consumes far more wafer capacity per bit, its revenue and profit per wafer fell behind ordinary server DRAM. Suppliers with heavier HBM exposure therefore faced a margin drag; those able to tilt mix towards CPU-side products enjoyed superior pricing power and profitability.
DDR5 server memory and SSDs are emerging as the huge revenue and margin drivers. Surging prices, strong volume growth from agentic demand and far better wafer economics than locked-in HBM make them highly profitable. Micron, with the smallest HBM share among the big three, grew DRAM revenue fastest and posted the highest operating margins. It pioneered data-centre SOCAMM, led capacity ramps, and saw its Core Data Center Business Unit (covering high-capacity DDR5, LPDRAM and storage) become the company’s fastest-growing segment. The winners in this phase are therefore those strongest in these CPU-centric memory types, not simply the HBM volume leaders.
I will be listening to the call for comments re the above
-
Spectacular result-worth a read. The take away is, there is no line of sight as to when supply catches demand. The imbalance will be worse in 2027 and worse again in 2028. 75% out output is already committed through 2027.
Regarding US mega caps. Micron is second only to Nvidia in terms of Operating Income generation. More than GOOG, Apple and Microsoft. And growing much faster.
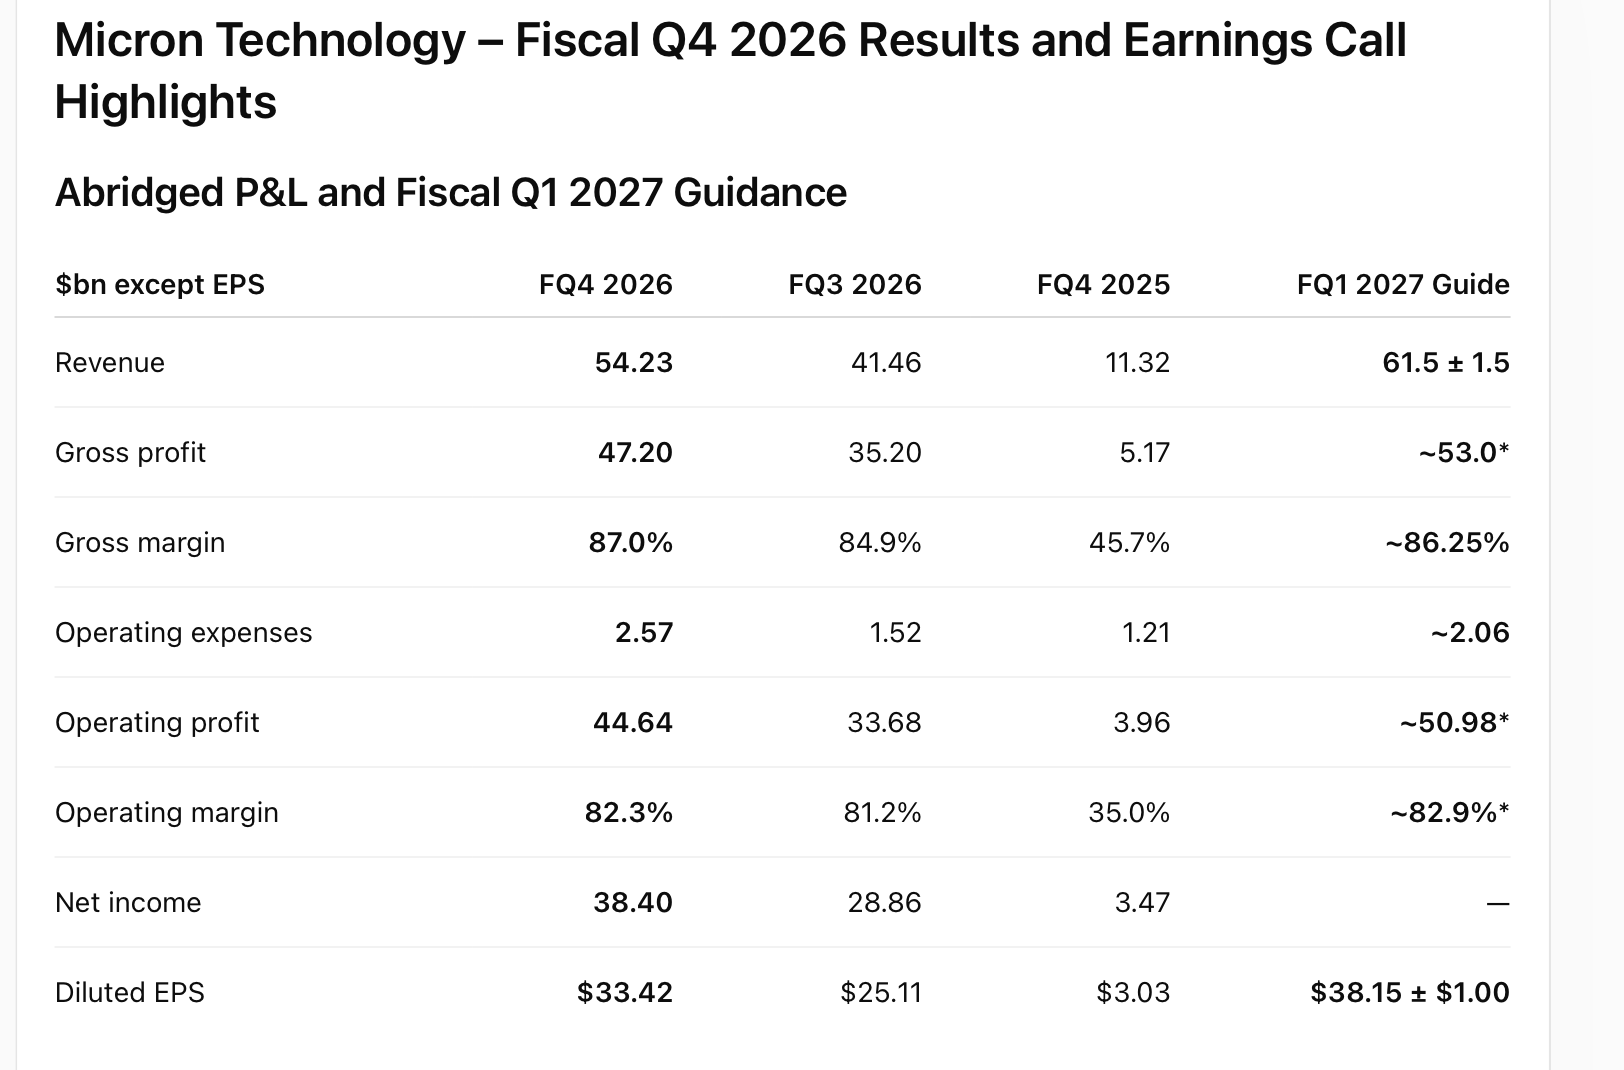
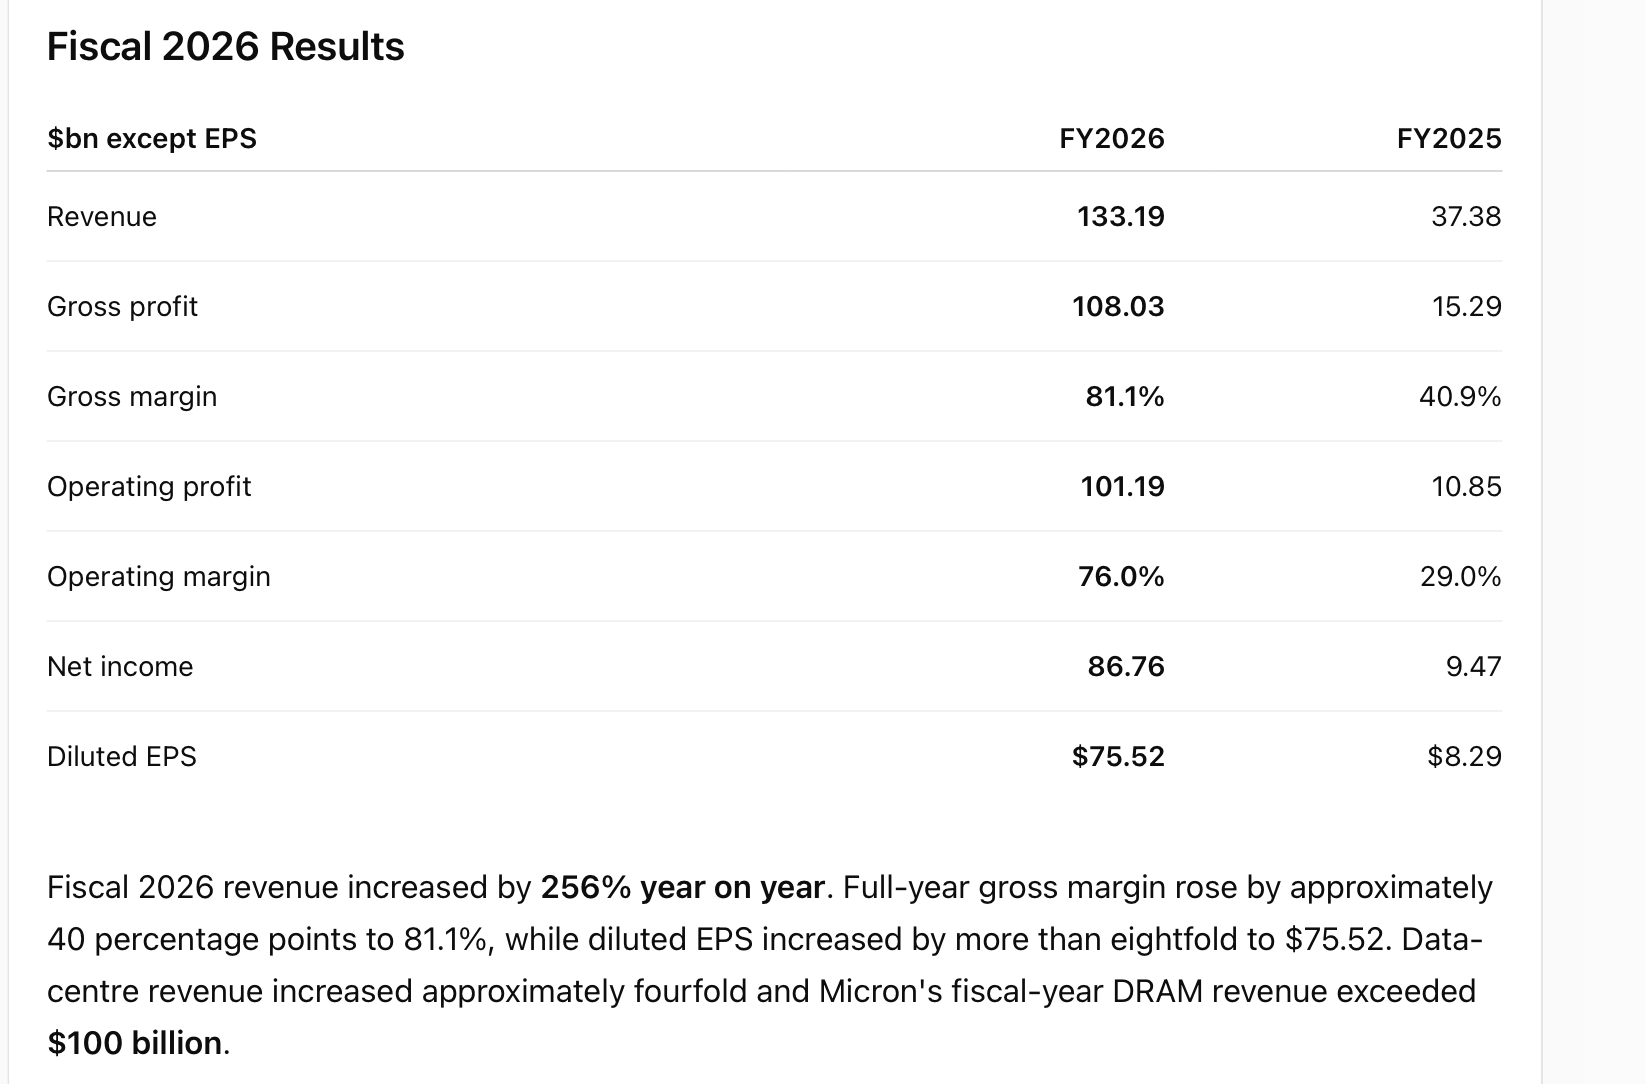
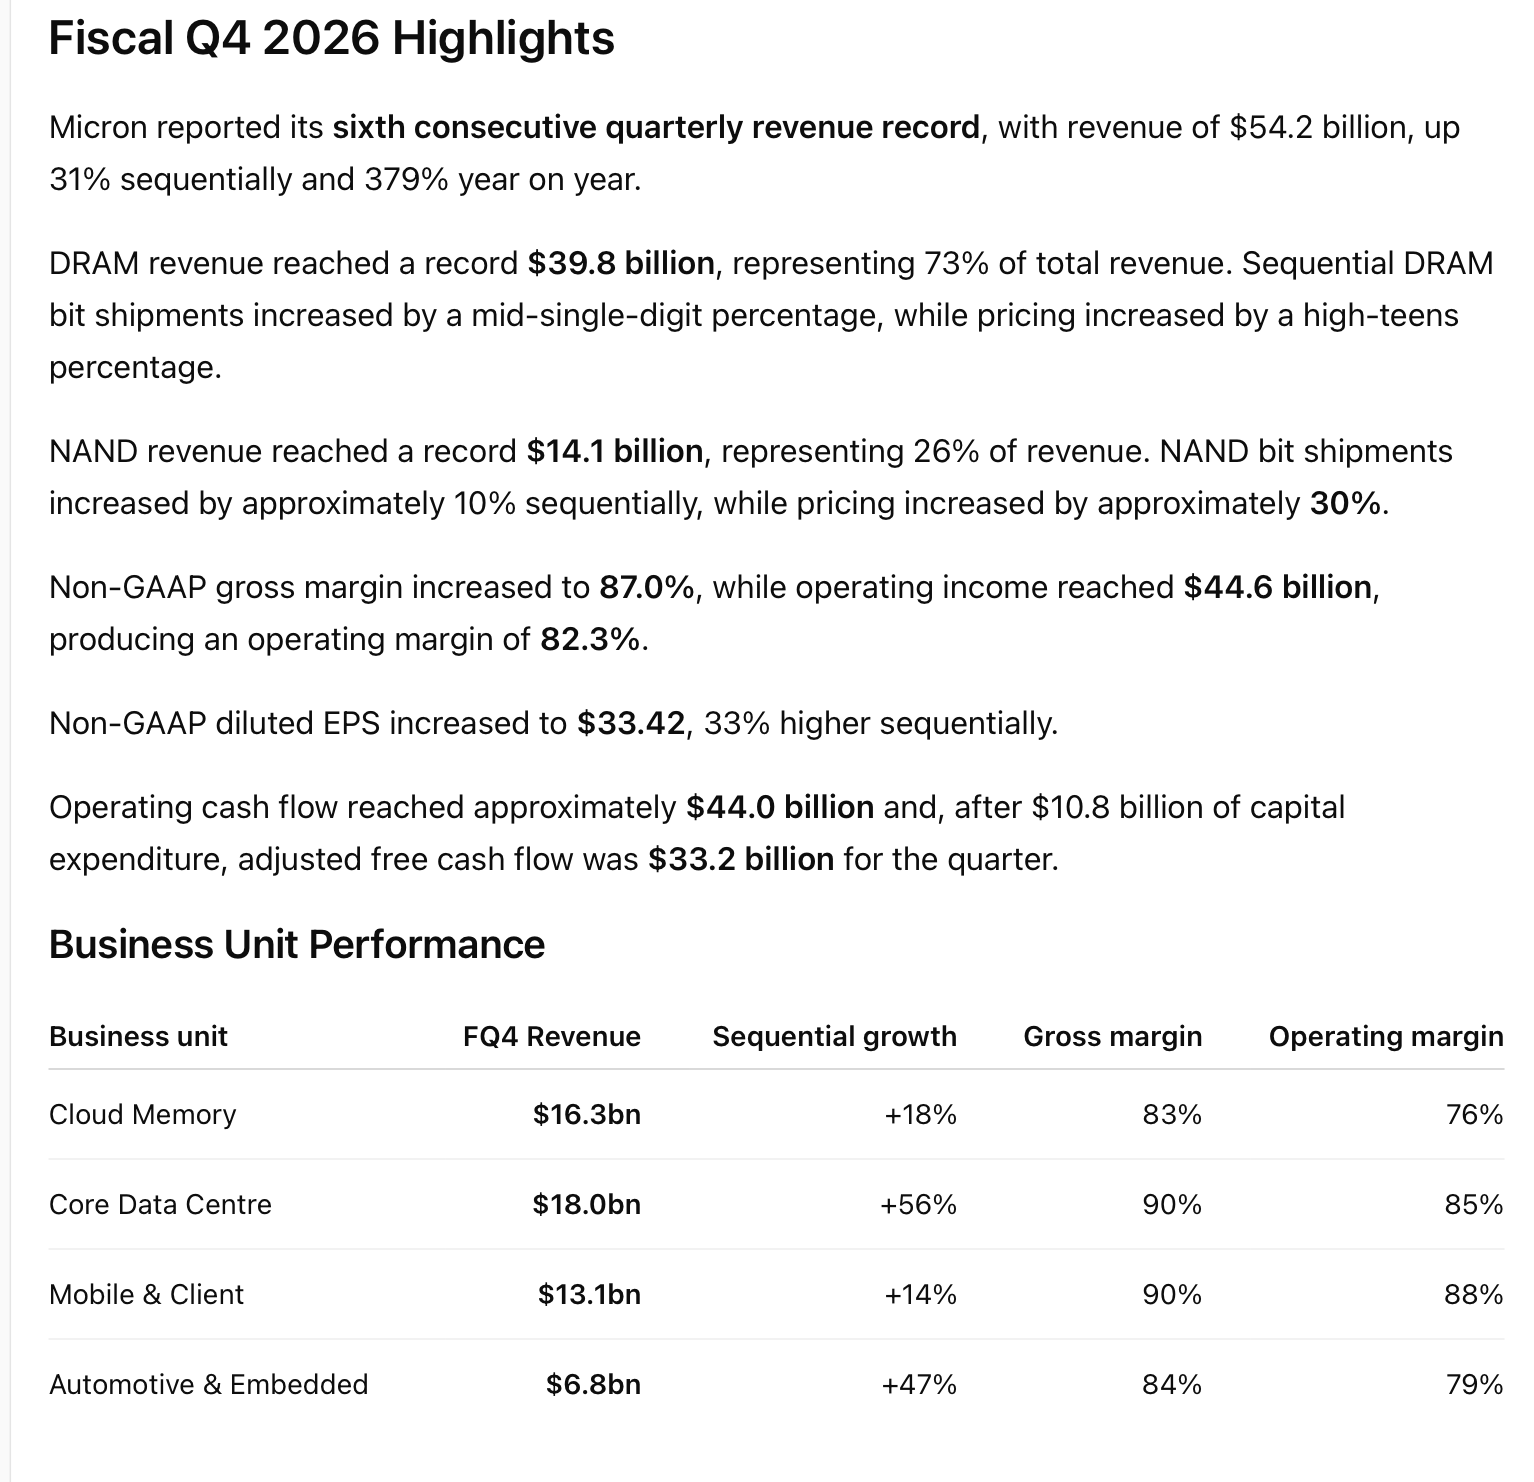
Fiscal Q1 2027 Outlook
Micron expects:
Revenue of $61.5 billion ± $1.5 billion
Non-GAAP gross margin of approximately 86.25%
Non-GAAP operating expenses of approximately $2.06 billion
Non-GAAP diluted EPS of $38.15 ± $1.00
Tax rate of approximately 15.5%
Capital expenditure of approximately $11.5 billion
Management expects sequential revenue growth in every quarter of fiscal 2027.
Fiscal Q1 is expected to represent the lowest gross margin of fiscal 2027, with gross margins expected to increase during the remainder of the year despite a more moderate pace of price increases.
Supply and Demand Outlook – 2027 and 2028
A central message from the earnings call was that the supply-demand imbalance is expected to become more pronounced in both calendar 2027 and 2028 than it was in 2026.
Micron expects the DRAM industry to remain supply constrained in both 2027 and 2028, with industry bit shipments growing by approximately the low-20s percentage range.
NAND is also expected to remain supply constrained in both years, despite industry bit shipment growth of approximately the mid-20s percentage range.
Management stated that the structural difference between demand growth and available supply is producing continuing market tightness and that additional cleanroom capacity will be required to narrow the gap.
Even after taking planned industry capacity additions into account, Micron said that it currently has no clear visibility as to when supply will catch up with demand.
During the Q&A, CEO Sanjay Mehrotra was specifically asked about concerns that 2027 could represent a peak in pricing and earnings. He reiterated that Micron expects supply conditions in both 2027 and 2028 to be tighter than in 2026.
The reasons highlighted included:
Long lead times for new fabrication facilities and cleanroom capacity
Gradual production ramps even after new facilities begin wafer output
Higher HBM production reducing the amount of conventional DRAM obtainable from a given quantity of wafer capacity
Lower productivity improvements from future semiconductor node transitions
Continued growth in AI model size
Longer context windows
Greater concurrency
Increased deployment of AI agents
High-teens percentage server unit growth expected in both 2026 and 2027
Management said these factors continued to support a favourable supply-demand environment and that customers were seeking additional memory supply rather than reducing their overall requirements.
2027 Output Already Heavily Committed
Micron stated that more than 75% of its calendar 2027 output is already committed.
This includes volumes covered by Strategic Customer Agreements as well as commitments from customers operating under more conventional annual arrangements.
Management also said that a majority of current customer discussions are already focused on calendar 2028 supply.
Customers are seeking longer-term supply assurance, with some Strategic Customer Agreements now extending through 2031.
Strategic Customer Agreements
Micron has now signed 26 Strategic Customer Agreements, which it estimates represent more than 35% of expected revenue through 2030.
Approximately three quarters of the expected revenue covered by these agreements has an established pricing framework. Most of these arrangements contain pricing bands with both floor and ceiling prices.
The remaining quarter is subject to periodic pricing negotiations based on prevailing market conditions.
Customer financial commitments associated with these agreements have increased to approximately $32 billion, with the great majority in the form of cash deposits.
Management continues to believe that Strategic Customer Agreements could eventually cover approximately 50% of revenue through 2030, while retaining sufficient capacity to serve customers outside these agreements.
$150 Billion Remaining Performance Obligations
Remaining performance obligations associated with Strategic Customer Agreements are approximately $150 billion.
The RPO figure only includes agreements where a defined pricing framework exists and is calculated from committed volumes and minimum contractual pricing.
Micron therefore regards the $150 billion RPO figure as conservative and expects eventual revenue from these agreements to substantially exceed the stated RPO.
The CFO also stated that even at contractual floor prices, Micron expects margins to remain meaningfully above the peak margins achieved in previous cycles.
HBM Outlook
HBM revenue grew faster than overall company revenue during fiscal Q4.
Micron has completed agreements covering the great majority of its calendar 2027 HBM bit supply, with prices materially higher than those agreed for 2026.
The higher 2027 pricing is expected to reduce the previous gross-margin difference between HBM and conventional DRAM.
Micron expects industry HBM bit demand to grow faster than conventional DRAM through calendar 2028.
The company is continuing its HBM4 ramp and is working with NVIDIA on a custom HBM4E implementation for future GPU and NVLink Fusion platforms.
Data Centre SSD and NAND
Fiscal Q4 data-centre SSD revenue was almost $10 billion, more than ten times the level achieved in the comparable period a year earlier.
Data-centre SSD represented more than two thirds of total NAND revenue.
Micron expects calendar 2026 to represent a fifth consecutive year of record market share in data-centre SSD.
Management highlighted growing opportunities from AI inference, KV-cache offload and the displacement of hard disk drives within data-centre infrastructure.
Cash Flow and Balance Sheet
Fiscal Q4 operating cash flow was approximately $44 billion.

Capital expenditure was approximately $10.8 billion, resulting in adjusted free cash flow of $33.2 billion.
Micron ended the quarter with:
$73.5 billion of cash and investments (Buybacks! post 9 Dec 26)
Approximately $5.2 billion of debt
Net cash of approximately $68.3 billion
Customer cash deposits of approximately $12.7 billion
The company received two credit-rating upgrades during the quarter and ended the period rated BBB+ or equivalent by all three major rating agencies.
Management expects free cash flow in fiscal Q1 2027 to be significantly higher than the $33 billion generated in fiscal Q4, based on the current revenue, margin and capital expenditure outlook.
Capital Expenditure
Micron expects approximately $11.5 billion of capital expenditure in fiscal Q1 and approximately $25 billion during the first half of fiscal 2027.
Second-half capital expenditure is expected to be higher than first-half spending.
A greater proportion of the increase will relate to construction rather than semiconductor manufacturing equipment, as Micron accelerates the availability of additional cleanroom space for 2028 and beyond.
Management indicated that new capacity would continue to be equipped in a disciplined manner as actual demand becomes clearer.
Manufacturing Expansion
Micron's principal manufacturing expansion programmes include:
Initial wafer output from Idaho ID1 in mid-calendar 2027
Initial output from Idaho ID2 in late calendar 2028
Additional Japanese DRAM production beginning in late calendar 2028
Meaningful shipments from the Tongluo, Taiwan facility in mid-calendar 2027
Initial output from the Singapore HBM advanced-packaging facility in early calendar 2027
New Singapore NAND capacity beginning production in the second half of calendar 2028
Initial wafer output from Micron's first New York fab expected in calendar 2030
Management stressed that initial wafer output does not immediately translate into substantial supply because new facilities require several quarters to ramp to meaningful production levels.
Product and Technology Highlights
Micron highlighted progress across several areas of its product portfolio:
Sampling of 512GB DDR5 RDIMMs capable of speeds of up to 9,200 MT/s
Multiple customer qualifications of 1-gamma 8,800 MT/s server RDIMMs
Server LPDDR SOCAMM revenue more than doubling sequentially
PCIe Gen 5 and Gen 6 SSD products shipping for KV-cache applications
Strong volume ramp of the 6600 ION SSD
Shipment of six-channel 1-gamma LPDDR5X for flagship mobile devices
AI workstation design wins with every Tier 1 OEM customer This relates to manufacturers such as Dell/HP/Leveno
Initial sampling of 1-gamma LPDDR6 products for physical-AI applications
Micron said its 1-gamma DRAM and G9 NAND processes are now its largest production nodes and are expected to become the highest-volume nodes in the company's history.
Physical AI
Micron identified autonomous vehicles, humanoid robotics and other intelligent autonomous systems as an emerging source of longer-term memory and storage demand.
Management said Level 4 and above autonomous vehicles typically require more than 200GB of memory and multiple terabytes of storage, more than an order of magnitude above current Level 2+ and Level 3 vehicles.
Humanoid robots are expected to require comparable memory and storage capacities.
Micron expects physical AI to become a significant demand driver for memory and storage towards the end of the decade.
Shareholder Returns
Micron intends to increase capital returns from 9 December 2026, following the second anniversary of the signing of its definitive CHIPS agreements.
Management expects share repurchases to be the principal means of returning excess capital.
The existing share-repurchase authorisation stood at approximately $2.2 billion at the time of the call, and management indicated that it expects to seek additional authorisation.
Over time, Micron intends to return 100% of excess cash to shareholders.
Principal Earnings Call Highlights
The earnings call substantially strengthened Micron's forward outlook beyond the headline fiscal Q4 results.
2027 and 2028 supply conditions: Micron expects the memory and storage supply-demand imbalance to be greater in both 2027 and 2028 than in 2026, with both DRAM and NAND remaining supply constrained.
No visible point of market balance: Management said it currently has no line of sight to when supply will catch up with demand.
Fiscal 2027 revenue: Revenue is expected to grow sequentially in every quarter of the fiscal year.
Fiscal 2027 margins: FQ1's approximately 86.25% gross margin is expected to be the lowest quarterly gross margin of the year, with margins rising thereafter. This is a big statement.
2027 supply commitments: More than 75% of calendar 2027 output is already committed, and customer discussions are increasingly centred on 2028 supply.
Long-term agreements: Micron has 26 Strategic Customer Agreements covering more than 35% of expected revenue through 2030, with customer financial commitments of approximately $32 billion.
Contracted backlog: Remaining performance obligations are approximately $150 billion, calculated using committed volumes and minimum pricing. Management expects realised revenue to exceed this figure.
HBM pricing: The majority of 2027 HBM supply has already been agreed at materially higher prices than in 2026.
Free cash flow: Fiscal Q4 produced $33.2 billion of free cash flow, with management expecting FQ1 free cash flow to be significantly higher.
Capital returns: Micron intends to increase shareholder returns from December 2026, principally through share repurchases.
Industry structure: Management believes Strategic Customer Agreements, long construction lead times, increasing HBM wafer requirements and AI-driven demand are materially changing the visibility and structure of the memory industry compared with previous cycles.
-
Impressive, beat even your projection there Adam, given how odd the markets are, I'll expect the price to drop now...
-
Spectacular result-worth a read. The take away is, there is no line of sight as to when supply catches demand. The imbalance will be worse in 2027 and worse again in 2028. 75% out output is already committed through 2027.
Regarding US mega caps. Micron is second only to Nvidia in terms of Operating Income generation. More than GOOG, Apple and Microsoft. And growing much faster.
Fiscal Q1 2027 Outlook
Micron expects:
Revenue of $61.5 billion ± $1.5 billion
Non-GAAP gross margin of approximately 86.25%
Non-GAAP operating expenses of approximately $2.06 billion
Non-GAAP diluted EPS of $38.15 ± $1.00
Tax rate of approximately 15.5%
Capital expenditure of approximately $11.5 billion
Management expects sequential revenue growth in every quarter of fiscal 2027.
Fiscal Q1 is expected to represent the lowest gross margin of fiscal 2027, with gross margins expected to increase during the remainder of the year despite a more moderate pace of price increases.
Supply and Demand Outlook – 2027 and 2028
A central message from the earnings call was that the supply-demand imbalance is expected to become more pronounced in both calendar 2027 and 2028 than it was in 2026.
Micron expects the DRAM industry to remain supply constrained in both 2027 and 2028, with industry bit shipments growing by approximately the low-20s percentage range.
NAND is also expected to remain supply constrained in both years, despite industry bit shipment growth of approximately the mid-20s percentage range.
Management stated that the structural difference between demand growth and available supply is producing continuing market tightness and that additional cleanroom capacity will be required to narrow the gap.
Even after taking planned industry capacity additions into account, Micron said that it currently has no clear visibility as to when supply will catch up with demand.
During the Q&A, CEO Sanjay Mehrotra was specifically asked about concerns that 2027 could represent a peak in pricing and earnings. He reiterated that Micron expects supply conditions in both 2027 and 2028 to be tighter than in 2026.
The reasons highlighted included:
Long lead times for new fabrication facilities and cleanroom capacity
Gradual production ramps even after new facilities begin wafer output
Higher HBM production reducing the amount of conventional DRAM obtainable from a given quantity of wafer capacity
Lower productivity improvements from future semiconductor node transitions
Continued growth in AI model size
Longer context windows
Greater concurrency
Increased deployment of AI agents
High-teens percentage server unit growth expected in both 2026 and 2027
Management said these factors continued to support a favourable supply-demand environment and that customers were seeking additional memory supply rather than reducing their overall requirements.
2027 Output Already Heavily Committed
Micron stated that more than 75% of its calendar 2027 output is already committed.
This includes volumes covered by Strategic Customer Agreements as well as commitments from customers operating under more conventional annual arrangements.
Management also said that a majority of current customer discussions are already focused on calendar 2028 supply.
Customers are seeking longer-term supply assurance, with some Strategic Customer Agreements now extending through 2031.
Strategic Customer Agreements
Micron has now signed 26 Strategic Customer Agreements, which it estimates represent more than 35% of expected revenue through 2030.
Approximately three quarters of the expected revenue covered by these agreements has an established pricing framework. Most of these arrangements contain pricing bands with both floor and ceiling prices.
The remaining quarter is subject to periodic pricing negotiations based on prevailing market conditions.
Customer financial commitments associated with these agreements have increased to approximately $32 billion, with the great majority in the form of cash deposits.
Management continues to believe that Strategic Customer Agreements could eventually cover approximately 50% of revenue through 2030, while retaining sufficient capacity to serve customers outside these agreements.
$150 Billion Remaining Performance Obligations
Remaining performance obligations associated with Strategic Customer Agreements are approximately $150 billion.
The RPO figure only includes agreements where a defined pricing framework exists and is calculated from committed volumes and minimum contractual pricing.
Micron therefore regards the $150 billion RPO figure as conservative and expects eventual revenue from these agreements to substantially exceed the stated RPO.
The CFO also stated that even at contractual floor prices, Micron expects margins to remain meaningfully above the peak margins achieved in previous cycles.
HBM Outlook
HBM revenue grew faster than overall company revenue during fiscal Q4.
Micron has completed agreements covering the great majority of its calendar 2027 HBM bit supply, with prices materially higher than those agreed for 2026.
The higher 2027 pricing is expected to reduce the previous gross-margin difference between HBM and conventional DRAM.
Micron expects industry HBM bit demand to grow faster than conventional DRAM through calendar 2028.
The company is continuing its HBM4 ramp and is working with NVIDIA on a custom HBM4E implementation for future GPU and NVLink Fusion platforms.
Data Centre SSD and NAND
Fiscal Q4 data-centre SSD revenue was almost $10 billion, more than ten times the level achieved in the comparable period a year earlier.
Data-centre SSD represented more than two thirds of total NAND revenue.
Micron expects calendar 2026 to represent a fifth consecutive year of record market share in data-centre SSD.
Management highlighted growing opportunities from AI inference, KV-cache offload and the displacement of hard disk drives within data-centre infrastructure.
Cash Flow and Balance Sheet
Fiscal Q4 operating cash flow was approximately $44 billion.
Capital expenditure was approximately $10.8 billion, resulting in adjusted free cash flow of $33.2 billion.
Micron ended the quarter with:
$73.5 billion of cash and investments (Buybacks! post 9 Dec 26)
Approximately $5.2 billion of debt
Net cash of approximately $68.3 billion
Customer cash deposits of approximately $12.7 billion
The company received two credit-rating upgrades during the quarter and ended the period rated BBB+ or equivalent by all three major rating agencies.
Management expects free cash flow in fiscal Q1 2027 to be significantly higher than the $33 billion generated in fiscal Q4, based on the current revenue, margin and capital expenditure outlook.
Capital Expenditure
Micron expects approximately $11.5 billion of capital expenditure in fiscal Q1 and approximately $25 billion during the first half of fiscal 2027.
Second-half capital expenditure is expected to be higher than first-half spending.
A greater proportion of the increase will relate to construction rather than semiconductor manufacturing equipment, as Micron accelerates the availability of additional cleanroom space for 2028 and beyond.
Management indicated that new capacity would continue to be equipped in a disciplined manner as actual demand becomes clearer.
Manufacturing Expansion
Micron's principal manufacturing expansion programmes include:
Initial wafer output from Idaho ID1 in mid-calendar 2027
Initial output from Idaho ID2 in late calendar 2028
Additional Japanese DRAM production beginning in late calendar 2028
Meaningful shipments from the Tongluo, Taiwan facility in mid-calendar 2027
Initial output from the Singapore HBM advanced-packaging facility in early calendar 2027
New Singapore NAND capacity beginning production in the second half of calendar 2028
Initial wafer output from Micron's first New York fab expected in calendar 2030
Management stressed that initial wafer output does not immediately translate into substantial supply because new facilities require several quarters to ramp to meaningful production levels.
Product and Technology Highlights
Micron highlighted progress across several areas of its product portfolio:
Sampling of 512GB DDR5 RDIMMs capable of speeds of up to 9,200 MT/s
Multiple customer qualifications of 1-gamma 8,800 MT/s server RDIMMs
Server LPDDR SOCAMM revenue more than doubling sequentially
PCIe Gen 5 and Gen 6 SSD products shipping for KV-cache applications
Strong volume ramp of the 6600 ION SSD
Shipment of six-channel 1-gamma LPDDR5X for flagship mobile devices
AI workstation design wins with every Tier 1 OEM customer This relates to manufacturers such as Dell/HP/Leveno
Initial sampling of 1-gamma LPDDR6 products for physical-AI applications
Micron said its 1-gamma DRAM and G9 NAND processes are now its largest production nodes and are expected to become the highest-volume nodes in the company's history.
Physical AI
Micron identified autonomous vehicles, humanoid robotics and other intelligent autonomous systems as an emerging source of longer-term memory and storage demand.
Management said Level 4 and above autonomous vehicles typically require more than 200GB of memory and multiple terabytes of storage, more than an order of magnitude above current Level 2+ and Level 3 vehicles.
Humanoid robots are expected to require comparable memory and storage capacities.
Micron expects physical AI to become a significant demand driver for memory and storage towards the end of the decade.
Shareholder Returns
Micron intends to increase capital returns from 9 December 2026, following the second anniversary of the signing of its definitive CHIPS agreements.
Management expects share repurchases to be the principal means of returning excess capital.
The existing share-repurchase authorisation stood at approximately $2.2 billion at the time of the call, and management indicated that it expects to seek additional authorisation.
Over time, Micron intends to return 100% of excess cash to shareholders.
Principal Earnings Call Highlights
The earnings call substantially strengthened Micron's forward outlook beyond the headline fiscal Q4 results.
2027 and 2028 supply conditions: Micron expects the memory and storage supply-demand imbalance to be greater in both 2027 and 2028 than in 2026, with both DRAM and NAND remaining supply constrained.
No visible point of market balance: Management said it currently has no line of sight to when supply will catch up with demand.
Fiscal 2027 revenue: Revenue is expected to grow sequentially in every quarter of the fiscal year.
Fiscal 2027 margins: FQ1's approximately 86.25% gross margin is expected to be the lowest quarterly gross margin of the year, with margins rising thereafter. This is a big statement.
2027 supply commitments: More than 75% of calendar 2027 output is already committed, and customer discussions are increasingly centred on 2028 supply.
Long-term agreements: Micron has 26 Strategic Customer Agreements covering more than 35% of expected revenue through 2030, with customer financial commitments of approximately $32 billion.
Contracted backlog: Remaining performance obligations are approximately $150 billion, calculated using committed volumes and minimum pricing. Management expects realised revenue to exceed this figure.
HBM pricing: The majority of 2027 HBM supply has already been agreed at materially higher prices than in 2026.
Free cash flow: Fiscal Q4 produced $33.2 billion of free cash flow, with management expecting FQ1 free cash flow to be significantly higher.
Capital returns: Micron intends to increase shareholder returns from December 2026, principally through share repurchases.
Industry structure: Management believes Strategic Customer Agreements, long construction lead times, increasing HBM wafer requirements and AI-driven demand are materially changing the visibility and structure of the memory industry compared with previous cycles.
@Adam-Kay said in Micron Technology:
Over time, Micron intends to return 100% of excess cash to shareholders
is this in the form of dividends or share buy back?
-
Almost all buy backs (Treasury purchases). The implied yield on a stock buy back is currently 20%. It increases ones ownership percentage-dividends do not.
-
Impressive, beat even your projection there Adam, given how odd the markets are, I'll expect the price to drop now...
@SteveRutter -there are so many moving parts it's pure dart throwing really-which doesn't matter because the company is not being value anywhere near a reasonable valuation. Why, because currently the market thinks the plates stop spinning and margins will collapse.
-
Almost all buy backs (Treasury purchases). The implied yield on a stock buy back is currently 20%. It increases ones ownership percentage-dividends do not.
@Adam-Kay basically free money then - whats not to like
-
Morgan Stanley just said Micron will earn $500B in about two years.
"Micron will earn close to half the current market cap by the end of 2028, with most of that returned to shareholders."
