
Micron Technology
-
MU has become a trader's playground. The underlying fundamentals remain exceptionally strong, with DRAM supply tight, pricing rising and AI-driven demand continuing to accelerate. The market seems unable to decide whether to focus on short-term volatility or the extraordinary earnings and cash flow potential over the next several years. Personally, I'm focused on the latter. The daily price swings are largely noise.
-
Did i see some news about another Chinese memory chip etc thingy thats the best thing since sliced bread earlier this week
-
CXMT's DRAM 'breakthrough': a paper tiger dressed up as a Micron killer.
Another week, another breathless headline suggesting China's CXMT is about to threaten Micron's dominance in advanced memory. Apparently, announcing a new manufacturing process is now equivalent to successfully producing billions of reliable chips at competitive costs.
Rosenblatt analyst Kevin Cassidy described the supposed threat as a "paper tiger". That seems rather generous.
Let's deal with the facts.
CXMT's much-publicised 4F² architecture promises a theoretical 33% reduction in memory-cell area. Wonderful. A good analogy is the gap between climbing a ladder and climbing Everest . Where are the independently verified yields? Manufacturing costs? Customer qualifications? Commercial production volumes? There aren't any publicly demonstrated figures establishing that this process can compete with Micron.
And CXMT hasn't even demonstrated cost leadership with its existing DDR5. Industry estimates suggest its current manufacturing cost per bit is over 30% higher than that of the established DRAM leaders.
So we're supposed to believe that a manufacturer still playing catch-up on conventional DRAM is suddenly going to leapfrog Micron with an entirely new, considerably more complex architecture? On what evidence?
But here's what makes the entire scare story particularly ridiculous.
Even if CXMT somehow achieved technological parity tomorrow, it wouldn't magically solve the industry's capacity constraints. Advanced DRAM and HBM demand is absorbing enormous manufacturing resources, new capacity takes years to build and qualify, and the supply environment isn't transformed by a laboratory announcement.
And where exactly are the hyperscale customers lining up to install unproven Chinese DRAM in their multibillion-dollar AI data centres?
Microsoft? Amazon? Google? Meta?
These companies demand exceptionally high reliability, exhaustive qualification, proven supply continuity and strict security and procurement compliance. Geopolitical restrictions add another formidable obstacle.
Chinese DRAM achieving meaningful penetration of leading Western AI data centres is a prospect measured in years, if it happens at all. CXMT announcing a new cell architecture does absolutely nothing to change that.
Meanwhile, Micron is already manufacturing and shipping advanced memory at scale, investing in successive technology generations and benefiting from extraordinary structural demand.
CXMT isn't a credible near-term threat to Micron's advanced DRAM or HBM business. It is a potential longer-term competitor in parts of the commodity memory market, which is an entirely different proposition.
The bottom line: No proven commercial yields. No demonstrated cost advantage. No established hyperscaler qualifications for the new process. No evidence of meaningful near-term supply disruption.
Just a theoretical density improvement, an ambitious timetable and another round of market hysteria.
 All bark, no benchmark.
CXMT increasingly resembles a Chihuahua barking at three Rottweilers: Micron, Samsung and SK Hynix.
Plenty of noise about technological breakthroughs, but where is the independently verified evidence of competitive yields, production costs, operating margins and sustained high-volume manufacturing?
Announcing a process is easy. Producing billions of reliable DRAM chips at competitive yields and margins is an entirely different proposition.
And with a public-market valuation to justify, there's every incentive to keep the good-news machine running. -
BofA - Micron $MU - 10.25.26
Price target: $1550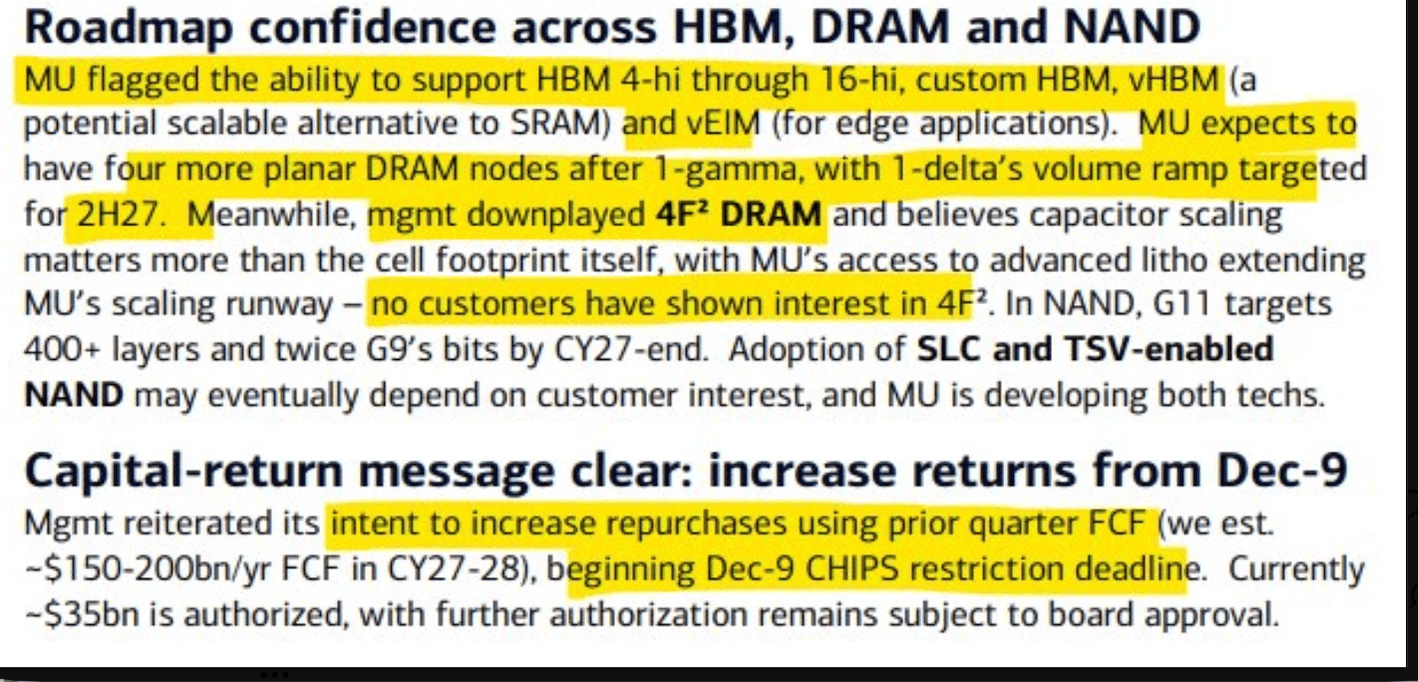
-
I’ll take that price target please
Bought a few for my ISA when they dipped last week -
@Adam-Kay when analysts give target prices, what is the duration, do they expect it in 3 months, a year or just what they think it will achieve at some point?
-
typically 12 months. cheers
-
SK Hynix reported last night
Summary and takeaways-all spectacular
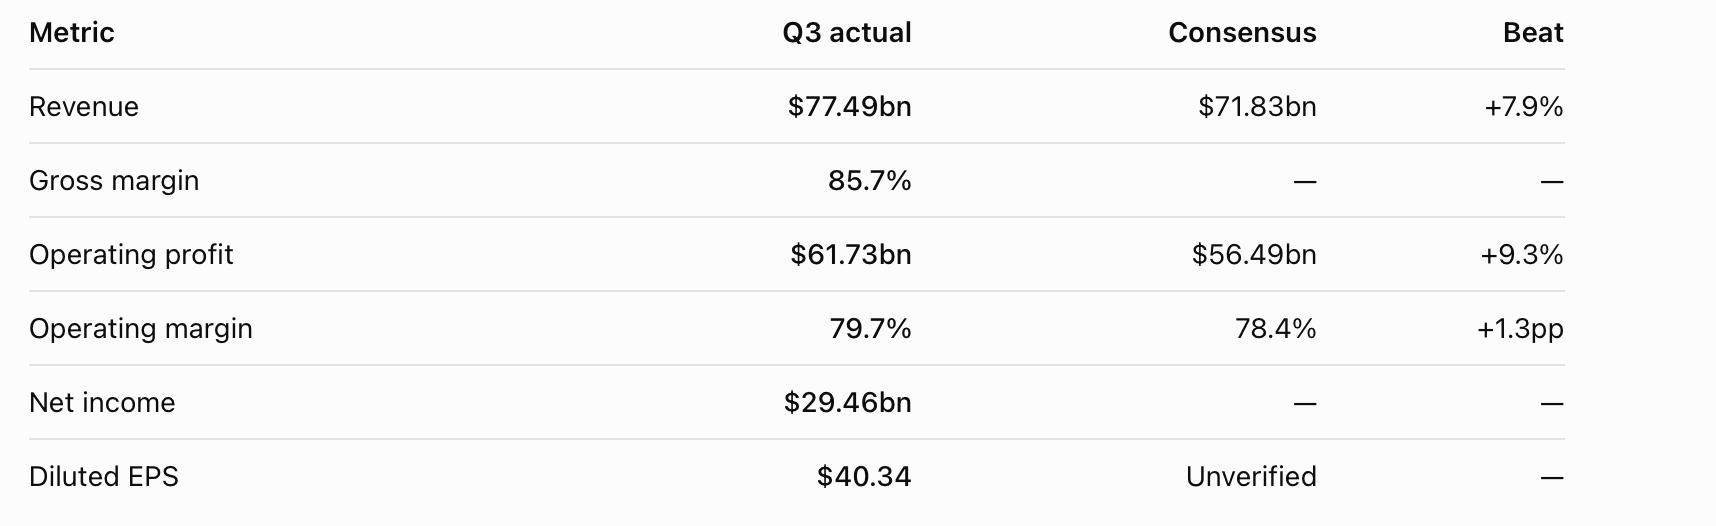
SK hynix delivered extraordinary results on 28 October 2026, with revenue up 328% year-on-year and an operating margin approaching 80%. The results comfortably exceeded analyst expectations. And one point you may notice. The operating margin is 80% but only 29.46B net income. They wrote off some investments plus took fx losses(weak ccy) to the tune of $24B so their normalised net income is closer to $48B-one quarter!We favour MU over SK for amongst other reasons-Korean IFRS can favour SK hynix’s reported profitability over Micron’s US GAAP through capitalised development costs, inventory write-down reversals and asset impairment reversals, potentially boosting margins without improving underlying economics.
Demand versus supply — the really important news
- HBM demand exceeds available supply by more than 2:1.
- DRAM and HBM capacity effectively sold out through 2029, including contracts currently being negotiated.
- Supply shortages expected through 2030, despite planned capacity expansions.
 (burry?)

- 2027 DRAM demand growth: mid-20%.
- 2027 NAND demand growth: high teens.
- 2027 revenue and profit: management expects both to be significantly higher than 2026.
Indicator Management outlook
Q4 DRAM shipment growth Mid-20% sequentially
Q4 NAND shipment growth Mid-single digits
Q4 HBM4 To overtake HBM3E in volume and revenue
2027 DRAM demand growth Mid-20%
2027 NAND demand growth High teens
Memory supply shortages Expected through 2030
2027 capital expenditure Significant increase
Long-term contracts 14 customers, covering over 50% of 2027–28 capacity -
from the Apple call last night
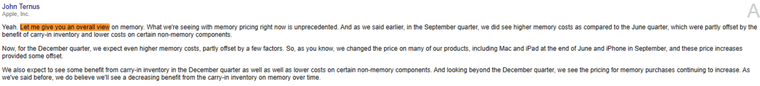
Look at what John Ternus is telling investors:
- Memory pricing is unprecedented. That's an extraordinary admission from a company with Apple's purchasing power.
- Prices rose in the September quarter and will rise further in December.
- Prices will continue increasing beyond December. This isn't being described as a temporary spike.
- Existing inventory is cushioning the impact, but that protection will progressively disappear.
- Apple has already increased product prices to help offset component inflation.
And here's the important bit: Apple is one of the largest, most sophisticated component purchasers in the world. If Apple cannot negotiate its way around rising memory prices, smaller customers are hardly going to fare better.
seems fitting to quote a real conversation from a decade ago
Back in 2015, Apple's notoriously aggressive procurement chief, Tony Blevins, threatened a SanDisk salesman that he would make its CEO, Sanjay Mehrotra, come crawling back to Apple on his knees.
Sanjay was then CEO of SanDisk. Today, of course, he's CEO of Micron.

-
Two supporting reports just out from JPM and Trendforce.
Micron: JPMorgan & TrendForce — November 2026
Conclusion: Exceptionally bullish for Micron's 2027–28 earnings outlook.The two research houses independently reinforce the same thesis: memory manufacturers are enjoying unusually strong pricing power, growing AI-related demand and constrained production capacity.
Key metric
JPMorgan: Q3 2026 DRAM ASP +23% QoQ
JPMorgan: 2027 HBM ASP forecast +96% YoY
TrendForce: 2027 blended HBM ASP forecast +121% YoY
TrendForce: 8-high HBM premium 10–20% per Gb versus 12-high
Supply outlook Tight through 2027, potentially beyond
HBM4/HBM4E Higher-value products driving the 2027 mixAn important additional development: TrendForce's 4 November bulletin says Samsung's 2027 HBM supply is sold out and SK hynix has already agreed its 2027 HBM4 volumes and prices.
This is especially significant because HBM production competes with conventional DRAM for wafer capacity, supporting pricing across both markets.
The main caveat is that these are industry forecasts, not Micron-specific realised prices. Nevertheless, the combination strongly supports the prospect of substantially higher Micron revenue, margins and free cash flow.
-
Hi Adam
Based on everything we know and all the above data etc ….
Can you make sense of the current MU share price -
This post is deleted!
-
I think Micron's current share price is largely explained by a combination of profit-taking, fear and political uncertainty rather than any deterioration in the underlying business.
After an extraordinary rise of around 900% over the past 18 months, plenty of investors are sitting on enormous profits. That naturally creates selling pressure, particularly given memories of previous DRAM downturns. People react to any news.
The US midterm results have added another layer of nervousness, with concerns about Democratic opposition to data-centre developments. Personally, I think the market is overreacting. AI infrastructure investment isn't going to stop. If certain states make development difficult, projects can move elsewhere, including overseas.
Meanwhile, the fundamentals look exceptionally strong:
Demand continues to accelerate, particularly for DRAM and HBM, while supply remains constrained and memory prices continue rising.
The supply chain is consistently warning of prolonged shortages. Memory manufacturers, equipment suppliers and industry analysts are increasingly talking about several years of tight supply, potentially extending towards the end of the decade. This is looking less like a traditional short memory cycle and more like a structural shortage.
UBS's projections are extraordinary. It forecasts global DRAM production rising from 36 exabytes in 2025 to 89 by 2030. Yet its more ambitious agentic-AI scenario suggests potential demand of 282 exabytes. That's a staggering 193-exabyte shortfall, with projected supply meeting less than one-third of potential demand. It's a scenario rather than a certainty, but illustrates the scale of the opportunity.
Long-term customer agreements are providing greater visibility into future demand and pricing than we've seen in previous memory cycles.
Micron's substantial share buyback programme becomes eligible to commence on 9 December. Management intends to return excess cash to shareholders over time, primarily through repurchases. Given the enormous cash generation, this could become a powerful additional source of demand for the shares and boost earnings per share.
I think the market is still looking backwards at Micron's historical boom-and-bust cycles rather than appreciating how fundamentally different this AI-driven demand cycle could be.
And remember, a share price rising 900% doesn't automatically make it expensive if earnings and free cash flow have grown even faster.
Of course, memory will always have an element of cyclicality, but when much of the supply chain is warning that demand could outstrip supply for years, potentially approaching a decade under aggressive AI scenarios, it's difficult to reconcile that outlook with fears of an imminent collapse.
My view is that the current weakness is predominantly profit-taking and fear, not deteriorating fundamentals. If the industry is even broadly correct about the duration of this supply shortage, Micron could be generating extraordinary earnings and cash flow for years to come.
-
Thanks Adam for reply which I agree with.
So are we buying more or selling some in the latest rebalance. -
Looking at the rebalance earlier in the week we were net sellers of Micron at $860-a very small percentage as it happened which simply reflects the then weight cf the target weight. Clearly very close
-
Have Micron just shelved opening another memory plant Taiwan
-
No that's not correct. This is all about one smaller Taiwan Labour Union demanding unreasonable pay which would equate to $1M per worker up from about 80k. Obviously the company isnt going to pay it. Who would so management have said , OK, you plan to strike and disrupt us, we will not expand the plant. It's a few billion expansion not a new build.
They've already reached an agreement with the larger union, but a smaller union representing fewer than 3,000 workers is challenging it despite substantial proposed pay increases.
Micron is demonstrating that future investment isn't guaranteed if labour disputes continue and I applaud it. Existing production is unaffected, and the suspended plant wasn't due to open until 2028.
Look at Micron's wider investment programme(250b so 2% in this case is immaterial):
Location
Planned investment
USA – New York, Idaho, Virginia and R&D
$200bn
Singapore – NAND and HBM expansion
$31bn
Japan – Hiroshima expansion
$9.3bn
Taiwan – Tongluo acquisition and expansion
$1.8bn acquisition, plus expansion
Taiwan – Taoyuan suspended project
$3–4.5bn
These are multi-year programmes, not all committed expenditure, and include R&D.
The suspended project is tiny relative to Micron's global expansion ambitions. If the dispute isn't resolved, Micron can redirect future capital elsewhere. And any disruption in supply will only cause prices to price so it's a win either way.
-
Thank you
-
Micron looks like its dropped another 11% today so far.
-
Micron looks like its dropped another 11% today so far.
@Jason-Knowles said in Micron Technology:
Micron looks like its dropped another 11% today so far.
Looks like it's DRAM kerfuffle rather than HBM, and I understand that HBM is where the $ is. Although that's uneducated guesswork from someone who doesn't know what he's talking about.