
Micron Technology
-
there are sales every day. MU(Treasury) is no different to any other buyer. It's all on the open market, no difference. $35B is circa 3% but the point is they are clearly signally that this is a quarterly proposal. 10%+ per annum
-
What on earth is going on with MU stock, its all over the place!
-
MU has become a trader's playground. The underlying fundamentals remain exceptionally strong, with DRAM supply tight, pricing rising and AI-driven demand continuing to accelerate. The market seems unable to decide whether to focus on short-term volatility or the extraordinary earnings and cash flow potential over the next several years. Personally, I'm focused on the latter. The daily price swings are largely noise.
-
Did i see some news about another Chinese memory chip etc thingy thats the best thing since sliced bread earlier this week
-
CXMT's DRAM 'breakthrough': a paper tiger dressed up as a Micron killer.
Another week, another breathless headline suggesting China's CXMT is about to threaten Micron's dominance in advanced memory. Apparently, announcing a new manufacturing process is now equivalent to successfully producing billions of reliable chips at competitive costs.
Rosenblatt analyst Kevin Cassidy described the supposed threat as a "paper tiger". That seems rather generous.
Let's deal with the facts.
CXMT's much-publicised 4F² architecture promises a theoretical 33% reduction in memory-cell area. Wonderful. A good analogy is the gap between climbing a ladder and climbing Everest . Where are the independently verified yields? Manufacturing costs? Customer qualifications? Commercial production volumes? There aren't any publicly demonstrated figures establishing that this process can compete with Micron.
And CXMT hasn't even demonstrated cost leadership with its existing DDR5. Industry estimates suggest its current manufacturing cost per bit is over 30% higher than that of the established DRAM leaders.
So we're supposed to believe that a manufacturer still playing catch-up on conventional DRAM is suddenly going to leapfrog Micron with an entirely new, considerably more complex architecture? On what evidence?
But here's what makes the entire scare story particularly ridiculous.
Even if CXMT somehow achieved technological parity tomorrow, it wouldn't magically solve the industry's capacity constraints. Advanced DRAM and HBM demand is absorbing enormous manufacturing resources, new capacity takes years to build and qualify, and the supply environment isn't transformed by a laboratory announcement.
And where exactly are the hyperscale customers lining up to install unproven Chinese DRAM in their multibillion-dollar AI data centres?
Microsoft? Amazon? Google? Meta?
These companies demand exceptionally high reliability, exhaustive qualification, proven supply continuity and strict security and procurement compliance. Geopolitical restrictions add another formidable obstacle.
Chinese DRAM achieving meaningful penetration of leading Western AI data centres is a prospect measured in years, if it happens at all. CXMT announcing a new cell architecture does absolutely nothing to change that.
Meanwhile, Micron is already manufacturing and shipping advanced memory at scale, investing in successive technology generations and benefiting from extraordinary structural demand.
CXMT isn't a credible near-term threat to Micron's advanced DRAM or HBM business. It is a potential longer-term competitor in parts of the commodity memory market, which is an entirely different proposition.
The bottom line: No proven commercial yields. No demonstrated cost advantage. No established hyperscaler qualifications for the new process. No evidence of meaningful near-term supply disruption.
Just a theoretical density improvement, an ambitious timetable and another round of market hysteria.
 All bark, no benchmark.
CXMT increasingly resembles a Chihuahua barking at three Rottweilers: Micron, Samsung and SK Hynix.
Plenty of noise about technological breakthroughs, but where is the independently verified evidence of competitive yields, production costs, operating margins and sustained high-volume manufacturing?
Announcing a process is easy. Producing billions of reliable DRAM chips at competitive yields and margins is an entirely different proposition.
And with a public-market valuation to justify, there's every incentive to keep the good-news machine running. -
BofA - Micron $MU - 10.25.26
Price target: $1550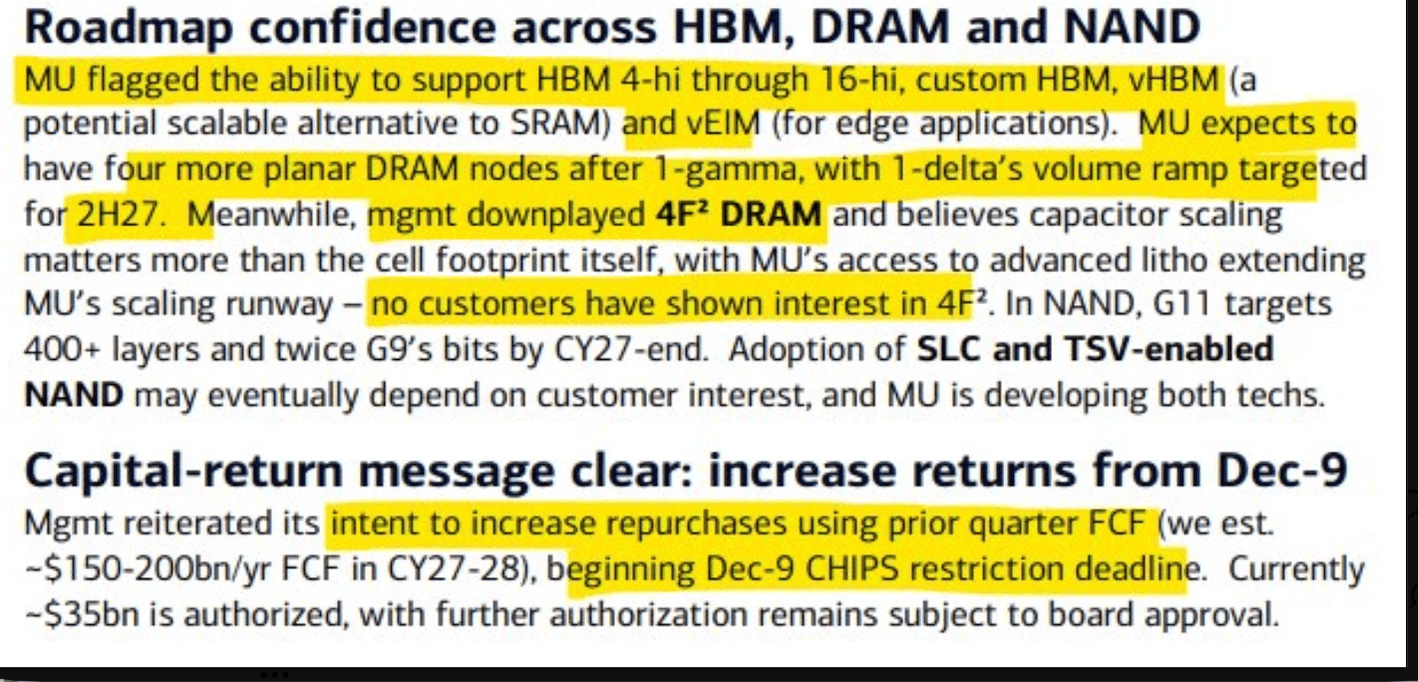
-
I’ll take that price target please
Bought a few for my ISA when they dipped last week -
@Adam-Kay when analysts give target prices, what is the duration, do they expect it in 3 months, a year or just what they think it will achieve at some point?
-
typically 12 months. cheers
-
SK Hynix reported last night
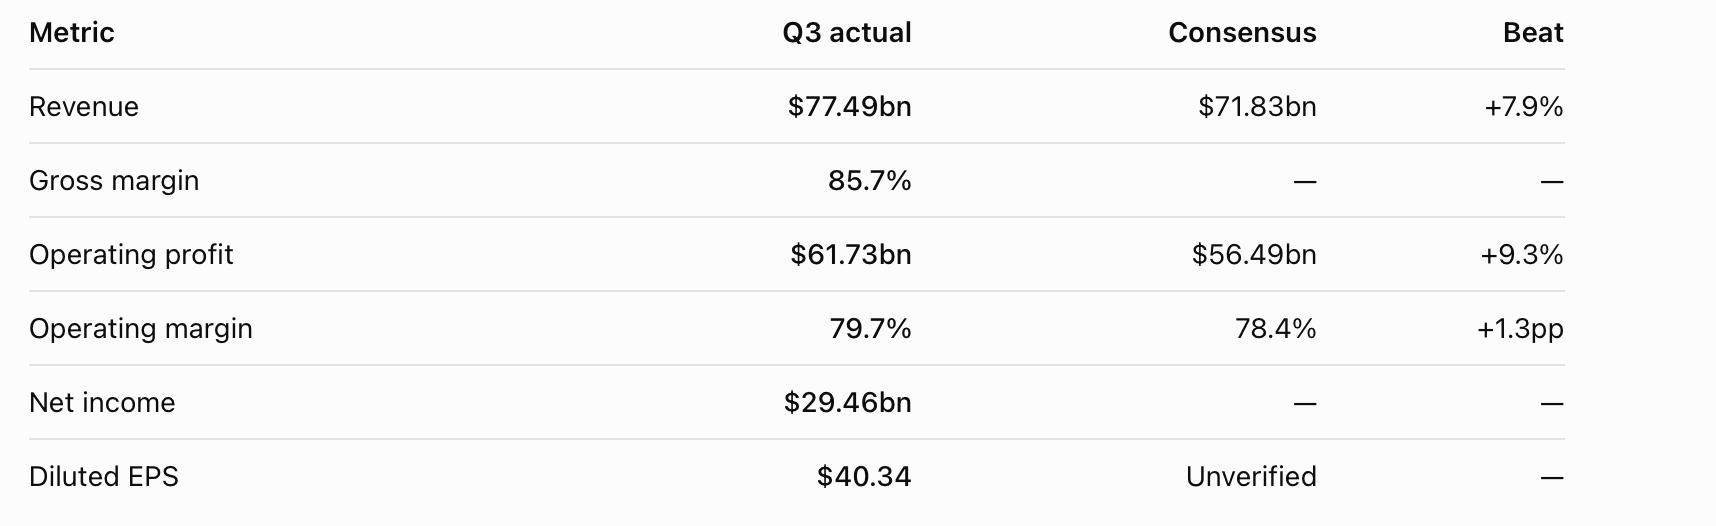
Summary and takeaways-all spectacular
SK hynix delivered extraordinary results on 28 October 2026, with revenue up 328% year-on-year and an operating margin approaching 80%. The results comfortably exceeded analyst expectations. And one point you may notice. The operating margin is 80% but only 29.46B net income. They wrote off some investments plus took fx losses(weak ccy) to the tune of $24B so their normalised net income is closer to $48B-one quarter!We favour MU over SK for amongst other reasons-Korean IFRS can favour SK hynix’s reported profitability over Micron’s US GAAP through capitalised development costs, inventory write-down reversals and asset impairment reversals, potentially boosting margins without improving underlying economics.
Demand versus supply — the really important news
- HBM demand exceeds available supply by more than 2:1.
- DRAM and HBM capacity effectively sold out through 2029, including contracts currently being negotiated.
- Supply shortages expected through 2030, despite planned capacity expansions.
 (burry?)

- 2027 DRAM demand growth: mid-20%.
- 2027 NAND demand growth: high teens.
- 2027 revenue and profit: management expects both to be significantly higher than 2026.
Indicator Management outlook
Q4 DRAM shipment growth Mid-20% sequentially
Q4 NAND shipment growth Mid-single digits
Q4 HBM4 To overtake HBM3E in volume and revenue
2027 DRAM demand growth Mid-20%
2027 NAND demand growth High teens
Memory supply shortages Expected through 2030
2027 capital expenditure Significant increase
Long-term contracts 14 customers, covering over 50% of 2027–28 capacity