
General News
-
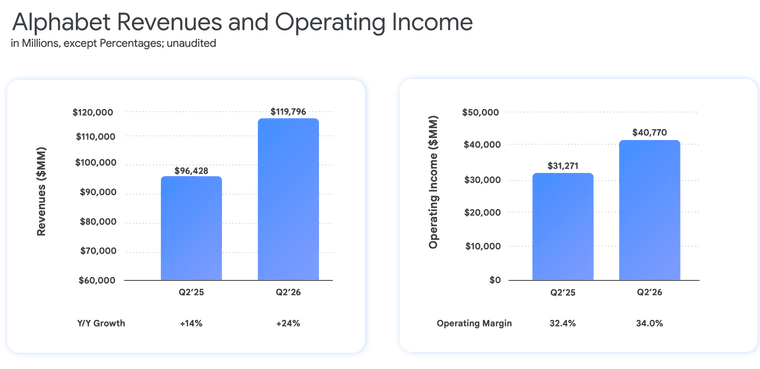
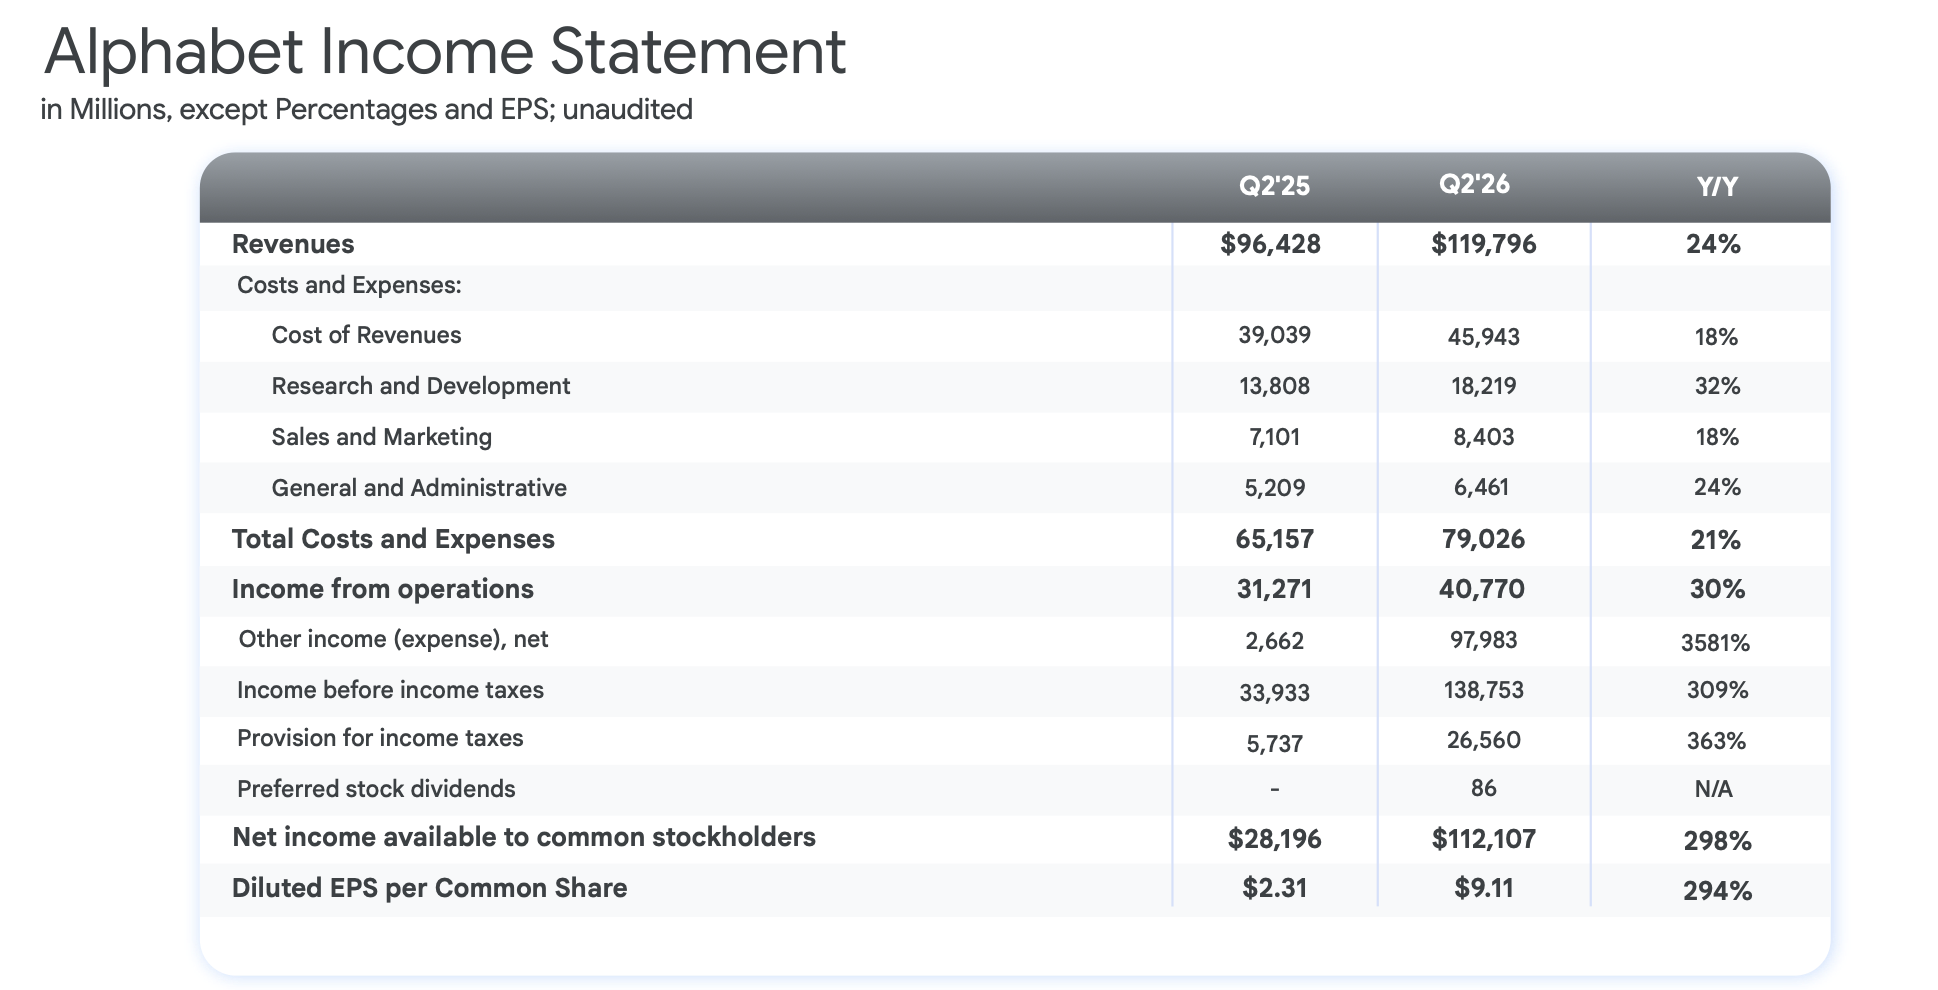
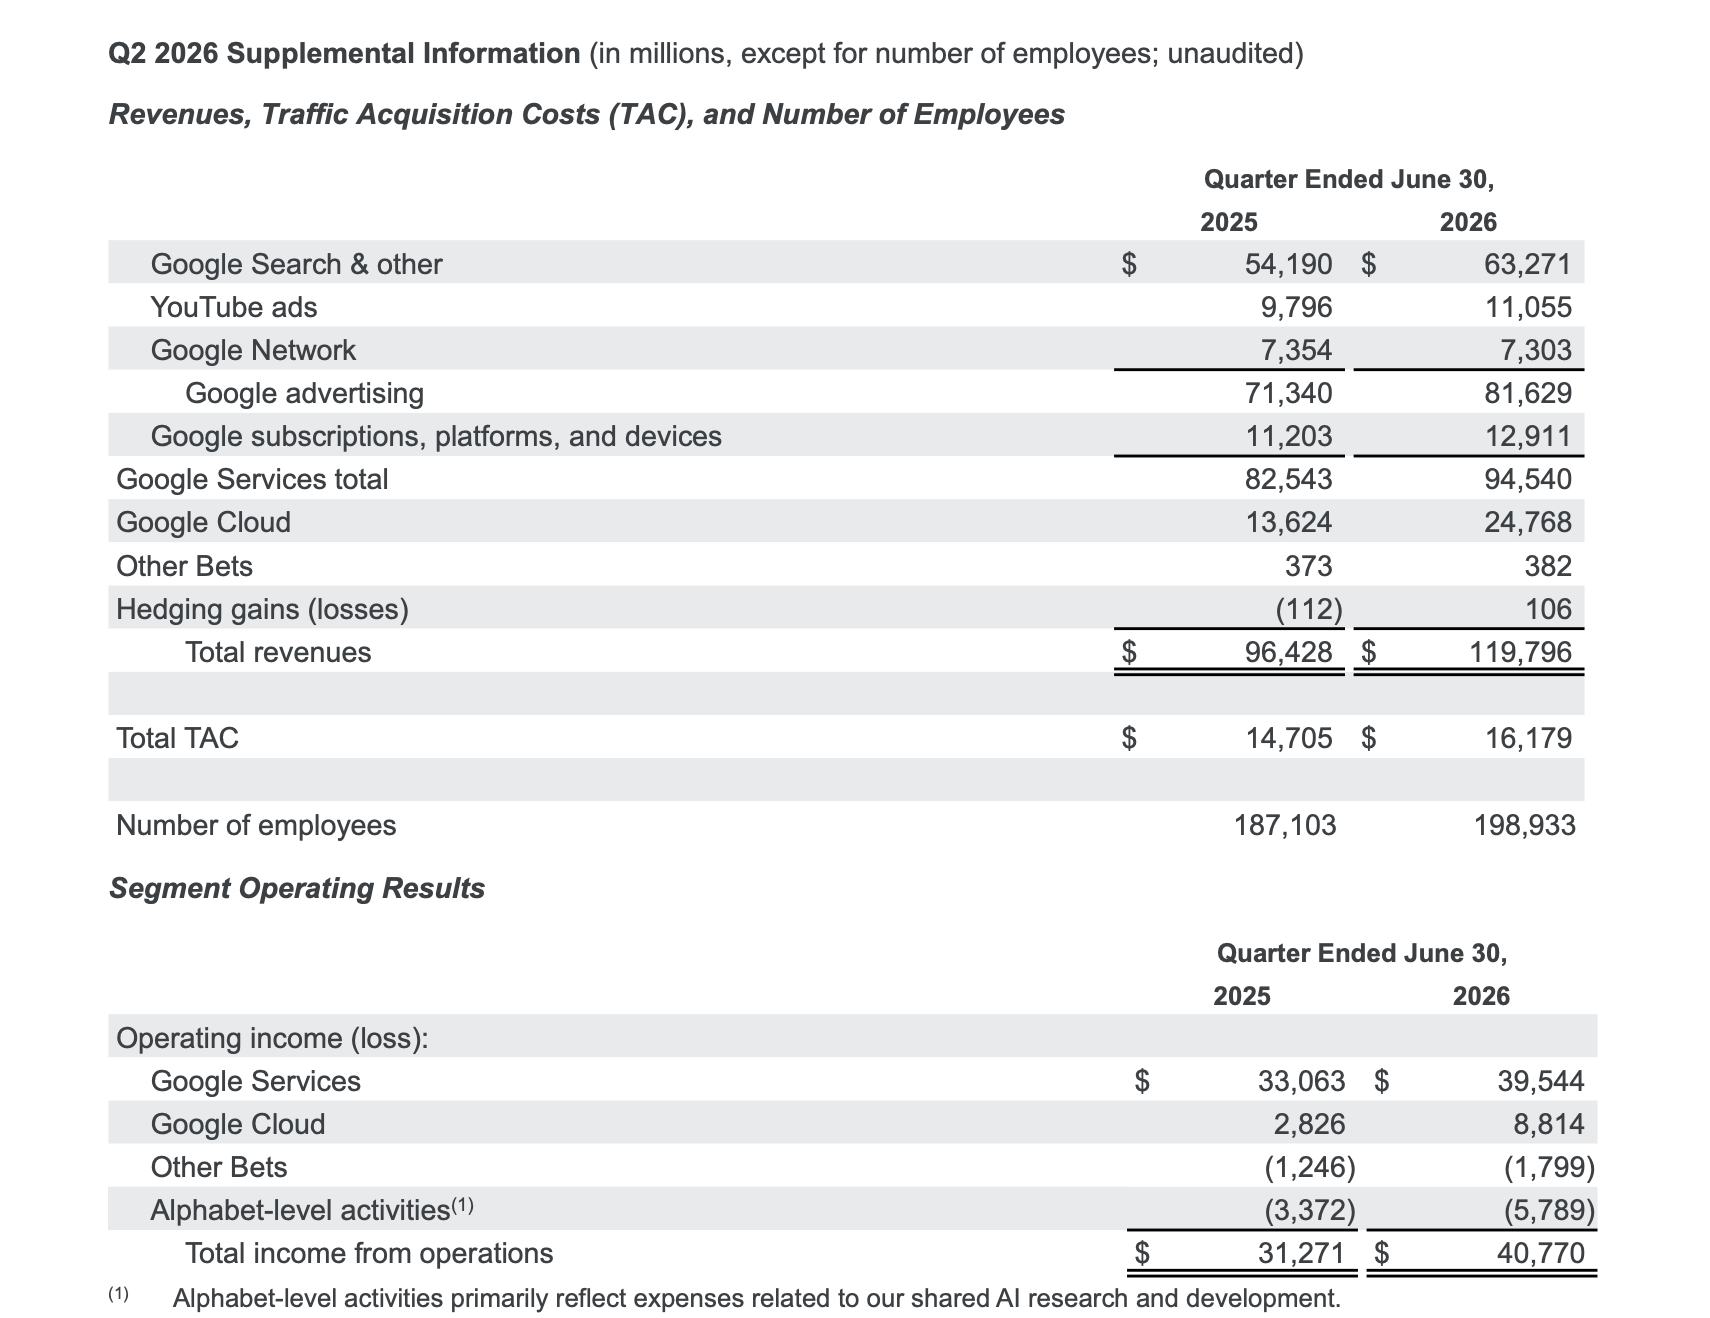
An outstanding result operationally-revenue +24% to just under 120B, operating income of 40.77B and an unrealised gain on investments of $98B (space x and anthropic). The stand out being GCP (cloud) +82%-current backlog RPO now stands at $516B. Google is accelerating capex spending well into $200B+ range, which the market won't like but 'tough'. They know what they are doing and have massive unmet demand which will be bridged in the short term whilst they aggressively build out their AI stack.
Notes from the call
Alphabet (Google) Q2 2026 Earnings Call – Key Takeaways
Financial highlights
Revenue: $119.8bn, up 24% year-on-year (23% constant currency).
Operating income: $40.8bn, up 30%.
Operating margin: 34%.
Operating cash flow: $39.1bn for the quarter.
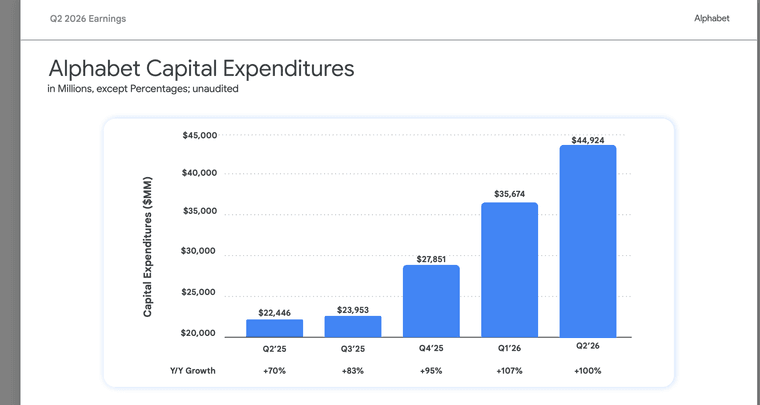
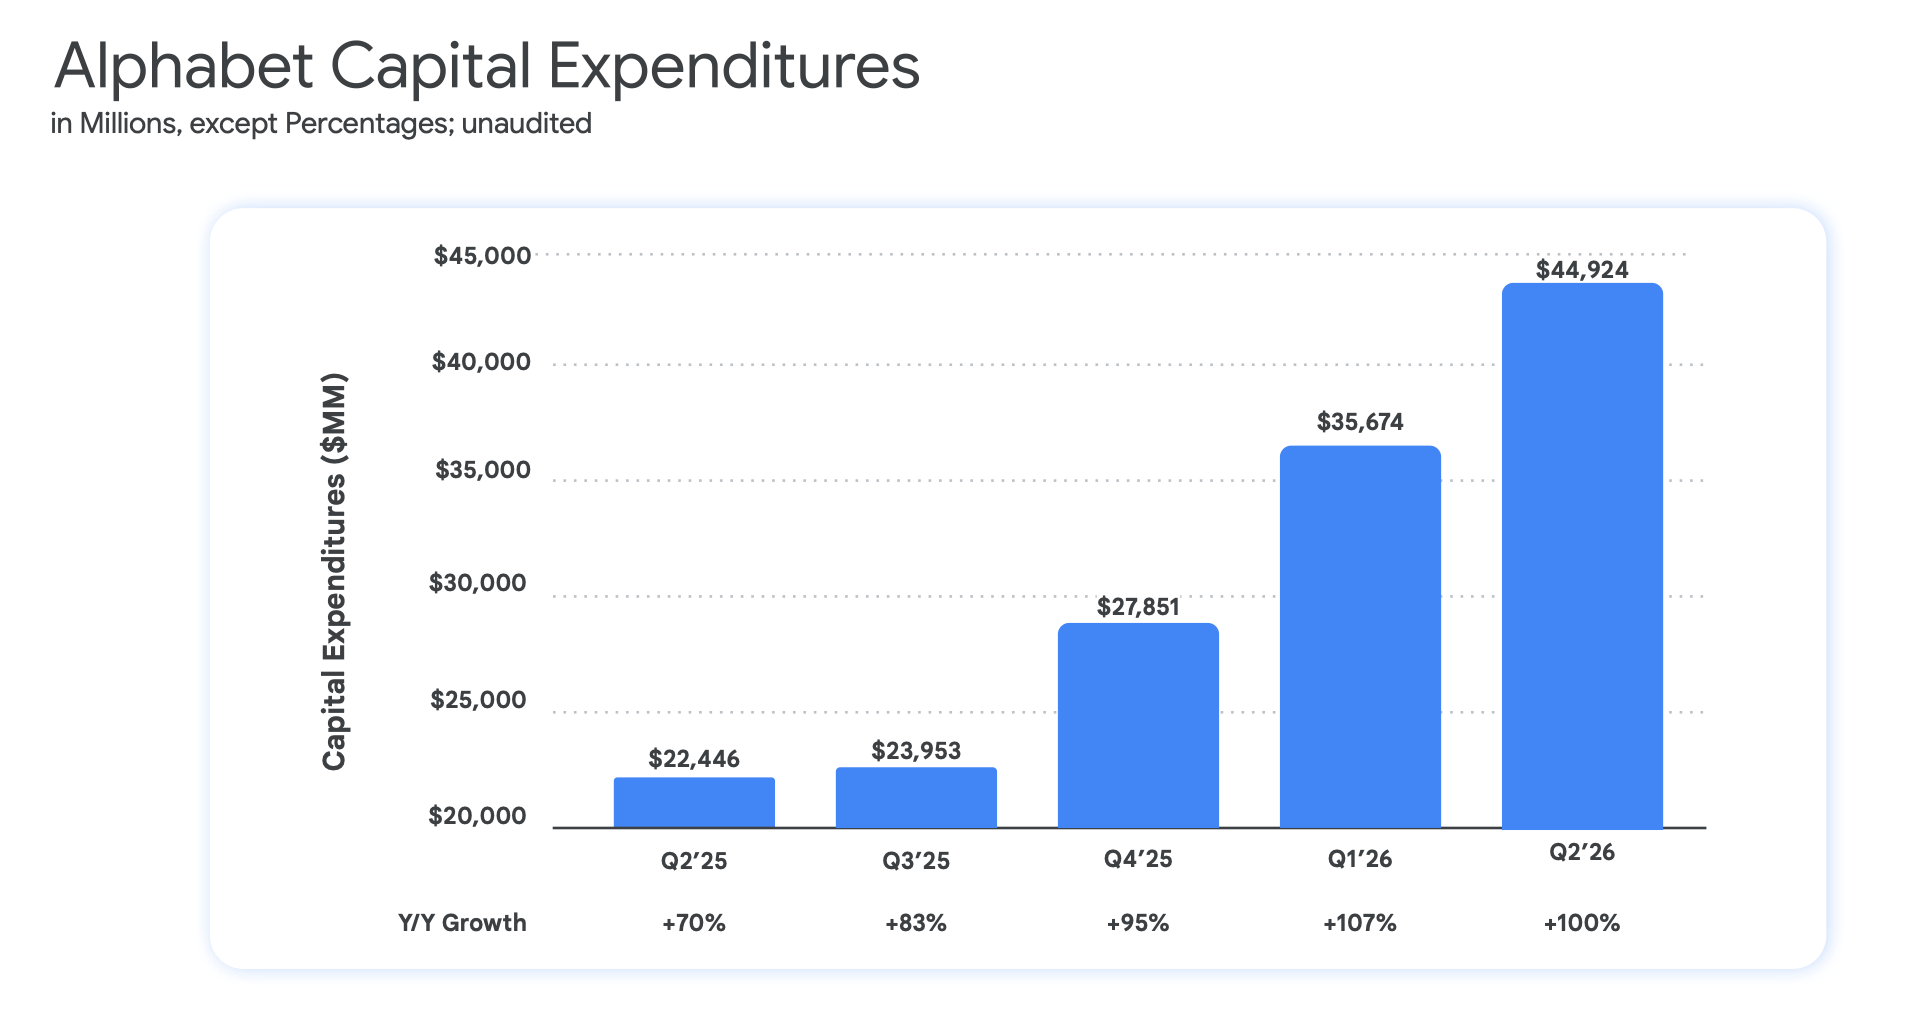
CapEx: $44.9bn in Q2, resulting in negative free cash flow of $5.9bn as investment accelerated.
Cash and marketable securities finished at $242.5bn.
Search remains exceptionally strong
The biggest surprise was the continued strength of Search.
Search & Other revenue grew 17%.
Management repeatedly stated that AI is expanding search usage rather than replacing it.
AI Mode has surpassed 1 billion monthly active users.
AI-powered searches are generating billions of website clicks each week.
Google says AI queries are creating incremental searches, rather than cannibalising traditional search.
Perhaps most importantly:
AI is allowing Google to monetise longer, more complex queries that previously generated little or no advertising revenue.
Gemini is improving:
query understanding;
advert relevance;
advertiser targeting; and
conversion rates.
Management suggested AI is making Search more monetisable, not less.
Cloud was extraordinary
Google Cloud produced one of the strongest quarters seen from any hyperscaler.
Revenue up 82% to $24.8bn.
Operating margin expanded from 20.7% to 35.6%.
Cloud operating profit more than tripled.
Growth came from:
core GCP;
AI infrastructure;
AI software;
Gemini Enterprise; and
the first recognition of TPU system sales.
Management noted that excluding TPU hardware sales, Cloud growth still accelerated materially.
Enormous backlog
Perhaps the most important number on the call:
Cloud backlog reached $514bn, increasing by more than $50bn in one quarter.
Management said:
over half should convert into revenue during the next 24 months;
the majority relates to normal GCP contracts;
TPU system sales are included but are a minority.
This backlog supports visibility well into 2027.
Demand still exceeds supply
One message dominated the call:
Google remains supply constrained.
They stated this repeatedly.
Demand exceeds available compute across:Search;
Gemini;
Cloud; and
model training.
To bridge the gap, Google will temporarily rent third-party compute capacity, which will:
slightly reduce Cloud margins in the short term;
allow Google to capture much larger multi-year contracts.
Management argued these deals remain highly attractive on a return-on-investment basis.
CapEx increased again
Full-year CapEx guidance was raised.
Previous:$180–190bn
New:
$195–205bn
The increase reflects faster deployment of AI infrastructure rather than cost overruns.
They also explicitly stated:CapEx will increase significantly again in 2027.
AI investment thesis becoming stronger
Sundar Pichai made one of his strongest comments to date.
He said that compared with a year ago, Google is more bullish about AI returns.Reasons include:
consumer AI adoption
enterprise AI demand
developer usage
cloud growth
He repeatedly described AI as still being in the very early innings.
Gemini momentum
Key statistics:
9 million monthly developers.
22 billion tokens processed per minute.
Gemini app reached 950 million monthly active users.
Daily users have tripled over the past year.
Gemini Enterprise is used by nearly 90% of Fortune 100 companies.
Google also confirmed:
Gemini 4 is now in training.
It is their largest pre-training run ever.
They intend to release models on a much faster cadence.
TPU strategy becoming much bigger
A major theme was Google's custom silicon.
Google is now:deploying TPUs internally
selling TPU systems directly to customers
including TPU contracts within Cloud backlog.
Revenue recognition has only just begun.
Management expects:a relatively small amount of TPU revenue during 2026;
the majority of those revenues arriving in 2027.
This represents an entirely new revenue stream.
Search monetisation improving
Advertising management gave several notable updates.
AI is improving:advert matching
advertiser ROI
conversion rates
monetisation of long-tail searches.Examples included:
AI Max campaigns delivering roughly 15% higher conversions.
Shopping advert relevance improving 20%.
Google continues to report that AI Overviews monetise well.
YouTube continues to strengthen
Advertising revenue up 13%.
Subscription revenue growing faster than advertising.
World Cup generated record engagement.
Connected TV continues to be a major growth driver.
Management sees substantial future opportunity from:
shoppable TV adverts;
Google Pay integration;
creator commerce;
Shorts.Waymo continues expanding.
Highlights:new sixth-generation vehicles;
continued geographic expansion;
management remains focused on scaling rather than spinning off the business.
No indication was given that Waymo will be separated from Alphabet.
Management tone
Perhaps the biggest takeaway was confidence.
Executives consistently described:demand as accelerating;
enterprise adoption as still in its infancy;
AI returns as becoming more compelling;
infrastructure investment as generating attractive long-term returns.
There was no indication that Google intends to moderate investment.
Key investor takeaways
Search appears to be benefiting from AI rather than suffering from it.
Google Cloud is becoming one of the fastest-growing large software businesses globally.
The $514bn Cloud backlog provides exceptional long-term revenue visibility.
AI demand continues to exceed available compute, supporting further infrastructure spending.
TPU systems are emerging as a meaningful new business that should contribute much more materially from 2027 onwards.
CapEx will remain extremely high, but management believes returns comfortably justify the investment.
Overall, the call reinforced the view that Alphabet is evolving from a predominantly advertising company into a diversified AI infrastructure, cloud and platform business while maintaining exceptional profitability. -
All sounds very positive, thanks for sharing and I note your $120b prediction was (again) much more accurate than the consensus view and that the Cloud growth exceeded your estimate.
Naturally the market price has dropped because rationality is only a small part of the market valuation process!
-
The comments from Google DeepMind executives suggest the company believes a significant AI capability leap is approaching. The current wave of AI investment is not simply about expanding existing applications; it is aimed at reaching the next stage where AI systems increasingly help create better AI systems through recursive self-improvement (RSI).
RSI means AI models assisting with research, software development, optimisation, training methods and data generation, creating a feedback loop where improved AI accelerates the development of even better AI. Google’s view is that the foundations of this process are already emerging, and betting against the current AI buildout would be unwise.
The scale of spending reinforces this confidence. The major technology companies are committing hundreds of billions of dollars to AI infrastructure. Industry AI capital expenditure is expected to exceed $700bn in 2026 after more than $400bn in 2025, with Google alone forecasting around $195bn-$205bn of 2026 capex. This investment covers GPUs, advanced memory, networking, data centres and power infrastructure required for the next generation of AI.
While revenues currently lag behind investment, this reflects a transition phase where infrastructure is being built ahead of widespread adoption. The comparison with previous industrial revolutions suggests the largest economic benefits may appear after the technology platform is established.
The next 12-36 months are likely to see major improvements in AI agents, coding ability, research assistance and automation. If AI systems begin materially accelerating AI development itself, progress could become much faster later this decade, potentially marking one of the biggest technological shifts in history. -
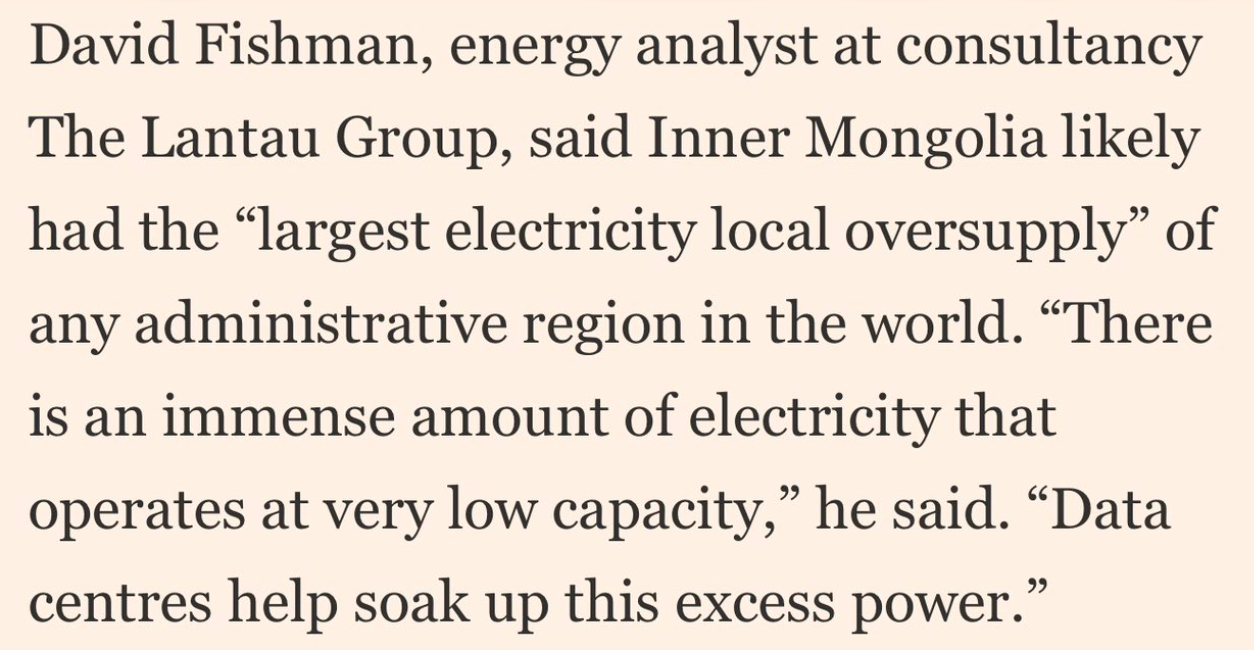
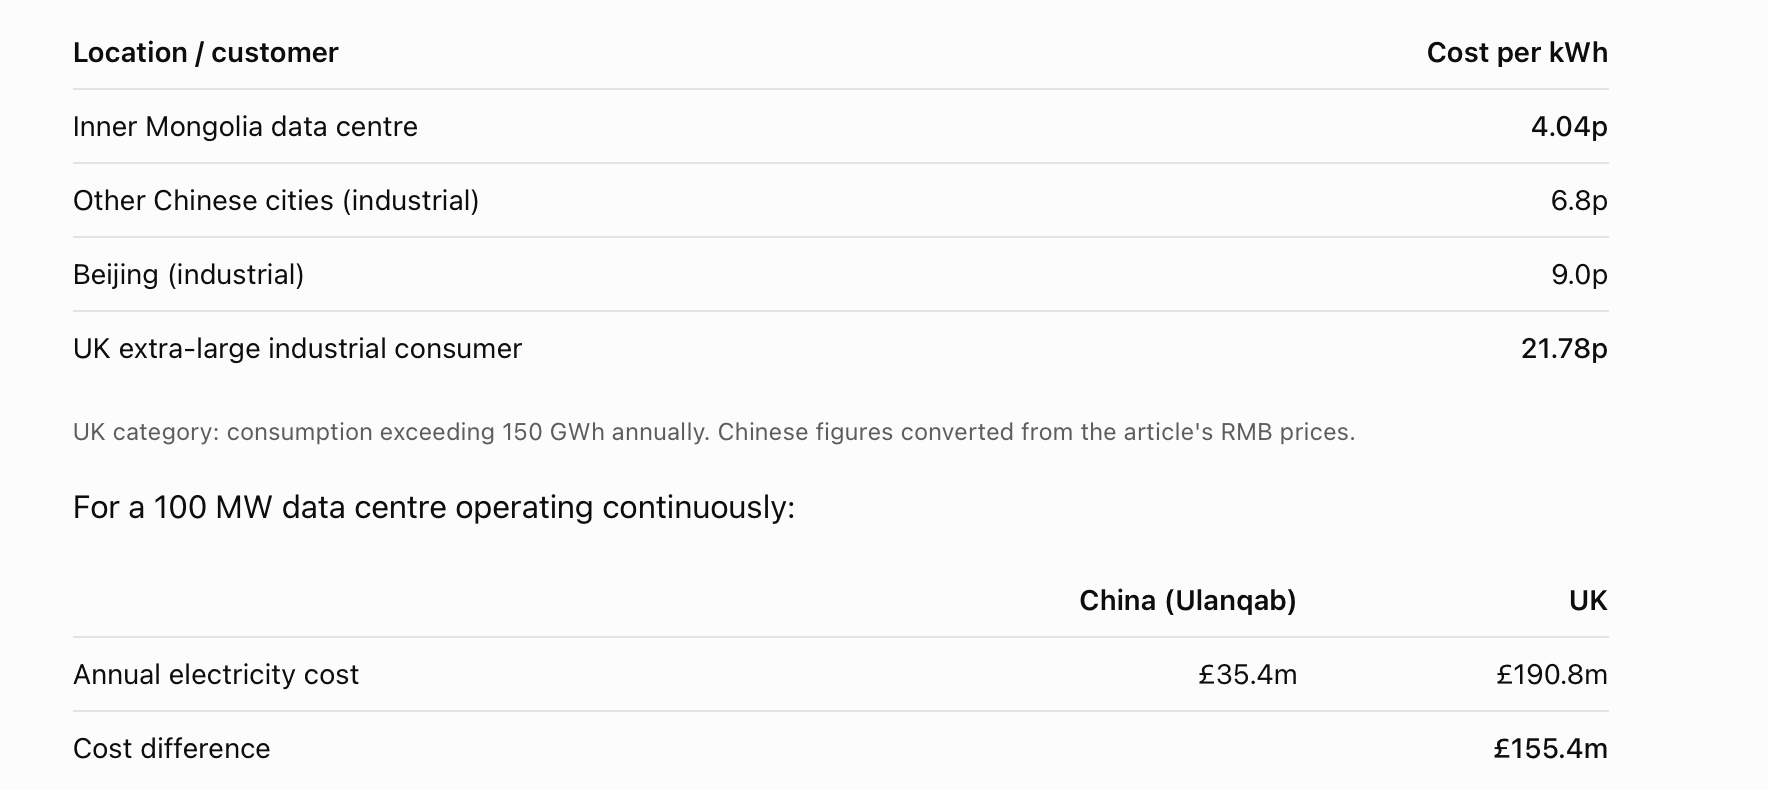
Interesting article on power costs in China(from the FT). Part of the reason there is a structural advantage vs the UK. Is our government listening
-
I'm not sure that is accurate. 33% is renewable(Mongolia) and 37% total China cf 50%(UK)
-
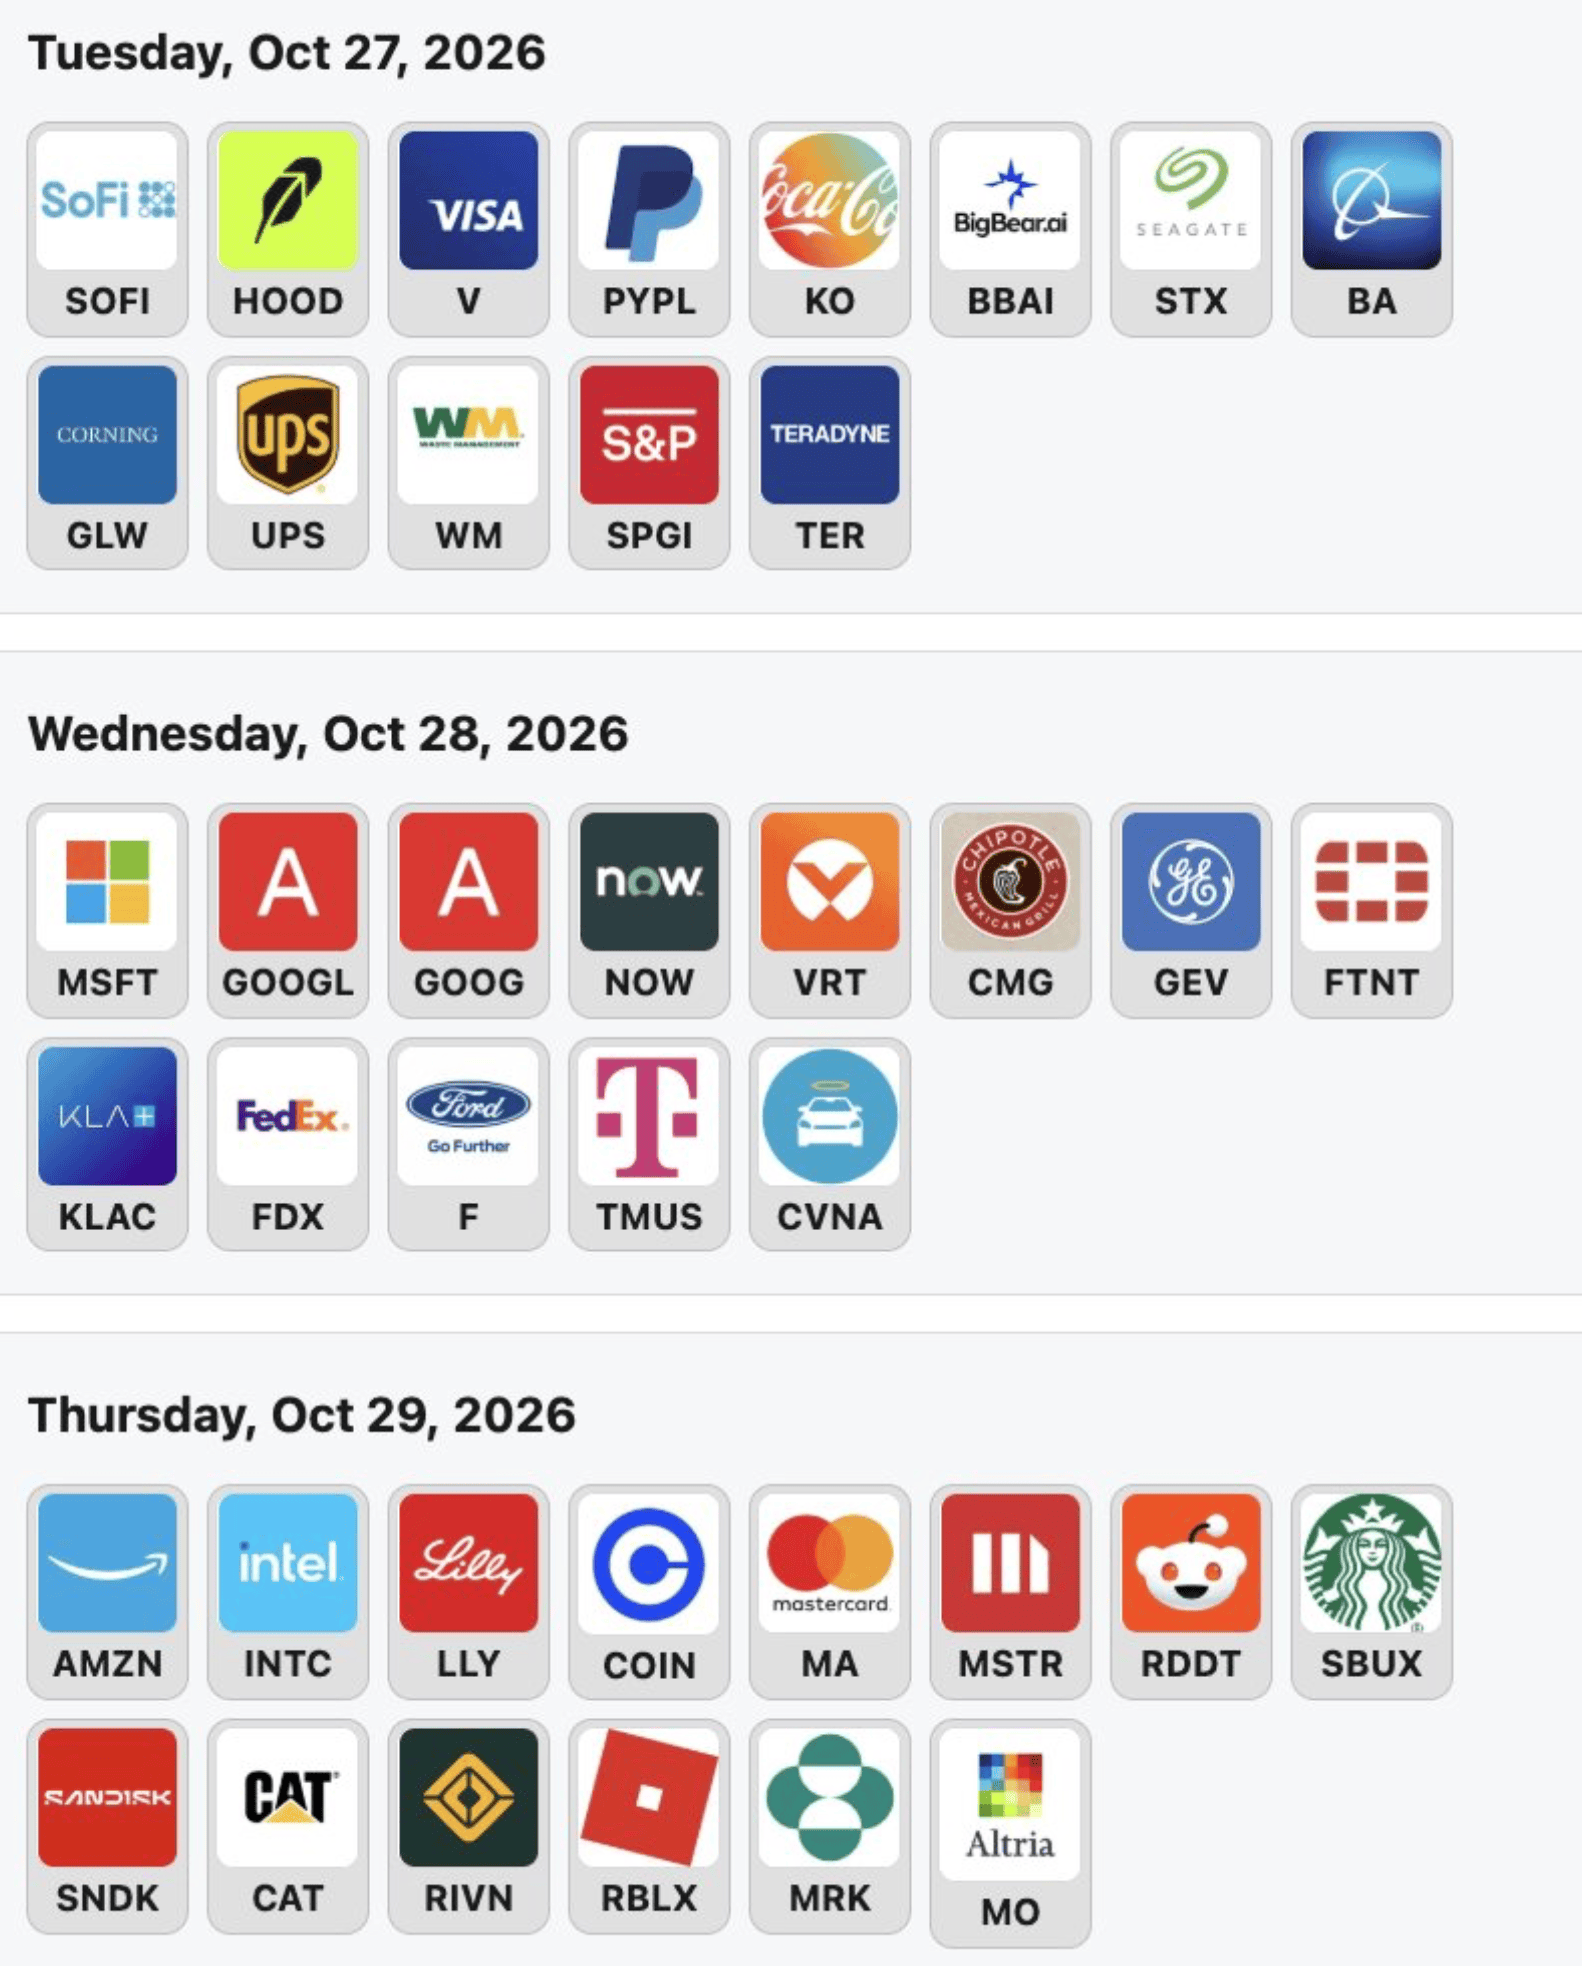
upcoming results
-
I doubt they can afford to do too much(harm) unless you're a bank, like to gamble a lot, maybe drink a lot
-
Do we have Sandisk in the funds
-
Hi- No we do not. The reasons are many
MU is a pure play manufacturer, Sandisk is a joint venture manufacturer (with Kioxia)
MU manufacturers both NAND and DRAM, Sandisk is solely, NAND
MU hold 3X the Nr of current patents
MU is at a scale Sandisk can never match
MU is exposed to markets growing at a faster paceSandisk is a good business, no doubts. I may have mentioned that I did a lot of work on it over 20 years ago when the business was run by Eli Harari and Sanjay Mehrotra (MU
 )
My philosophy is to pick the best of breed within a sector. EG Nvidia over AMD. And whilst AMD has appreciated more in the past year, you are now sitting with AMD on a multiple almost 4X greater(75!) but strangely with half the margins and half the growth. We will see how that plays out. Imo when people talk of bubbles this company is it.

