
General News
-
The comments from Google DeepMind executives suggest the company believes a significant AI capability leap is approaching. The current wave of AI investment is not simply about expanding existing applications; it is aimed at reaching the next stage where AI systems increasingly help create better AI systems through recursive self-improvement (RSI).
RSI means AI models assisting with research, software development, optimisation, training methods and data generation, creating a feedback loop where improved AI accelerates the development of even better AI. Google’s view is that the foundations of this process are already emerging, and betting against the current AI buildout would be unwise.
The scale of spending reinforces this confidence. The major technology companies are committing hundreds of billions of dollars to AI infrastructure. Industry AI capital expenditure is expected to exceed $700bn in 2026 after more than $400bn in 2025, with Google alone forecasting around $195bn-$205bn of 2026 capex. This investment covers GPUs, advanced memory, networking, data centres and power infrastructure required for the next generation of AI.
While revenues currently lag behind investment, this reflects a transition phase where infrastructure is being built ahead of widespread adoption. The comparison with previous industrial revolutions suggests the largest economic benefits may appear after the technology platform is established.
The next 12-36 months are likely to see major improvements in AI agents, coding ability, research assistance and automation. If AI systems begin materially accelerating AI development itself, progress could become much faster later this decade, potentially marking one of the biggest technological shifts in history. -
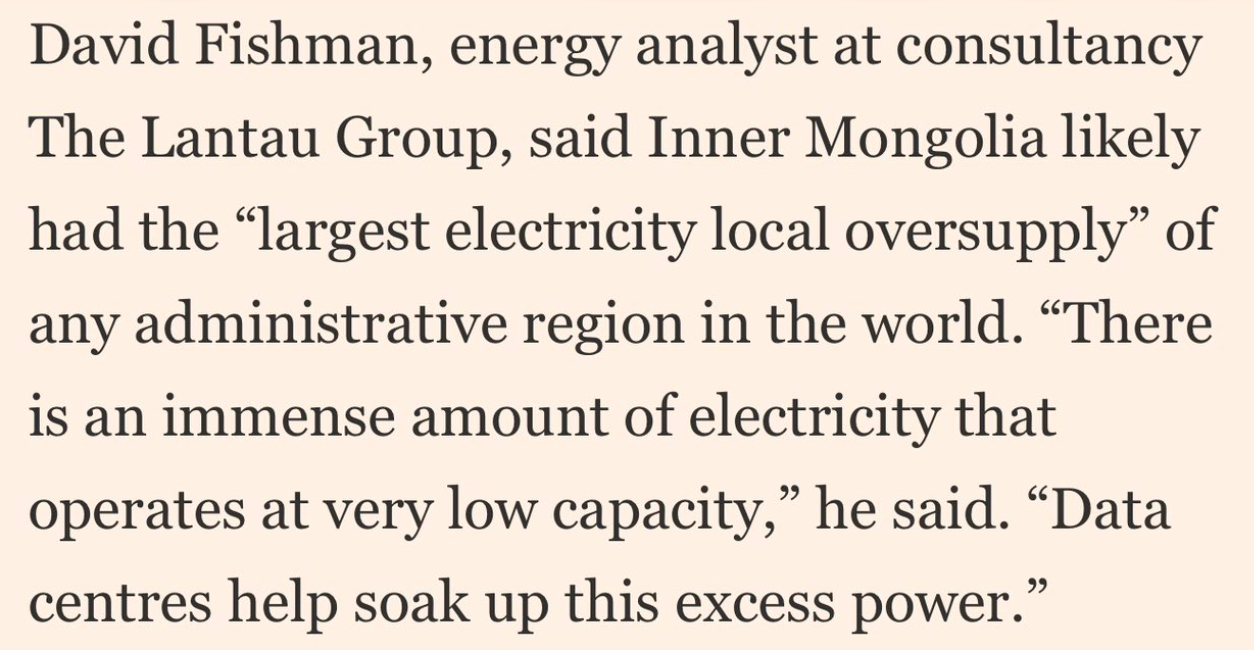
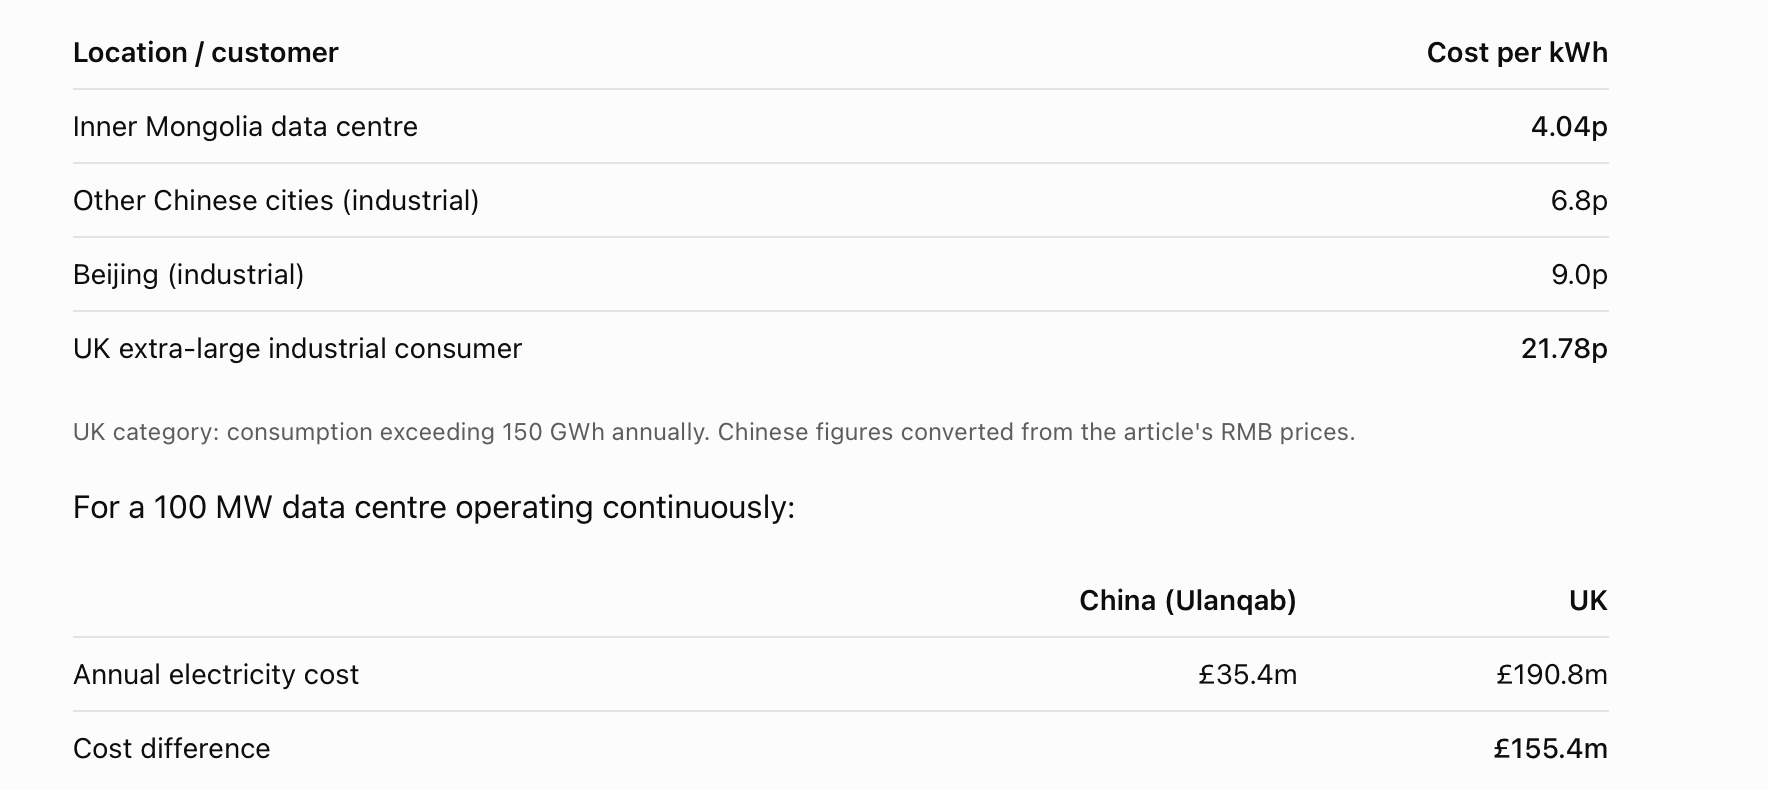
Interesting article on power costs in China(from the FT). Part of the reason there is a structural advantage vs the UK. Is our government listening
-
I'm not sure that is accurate. 33% is renewable(Mongolia) and 37% total China cf 50%(UK)
-
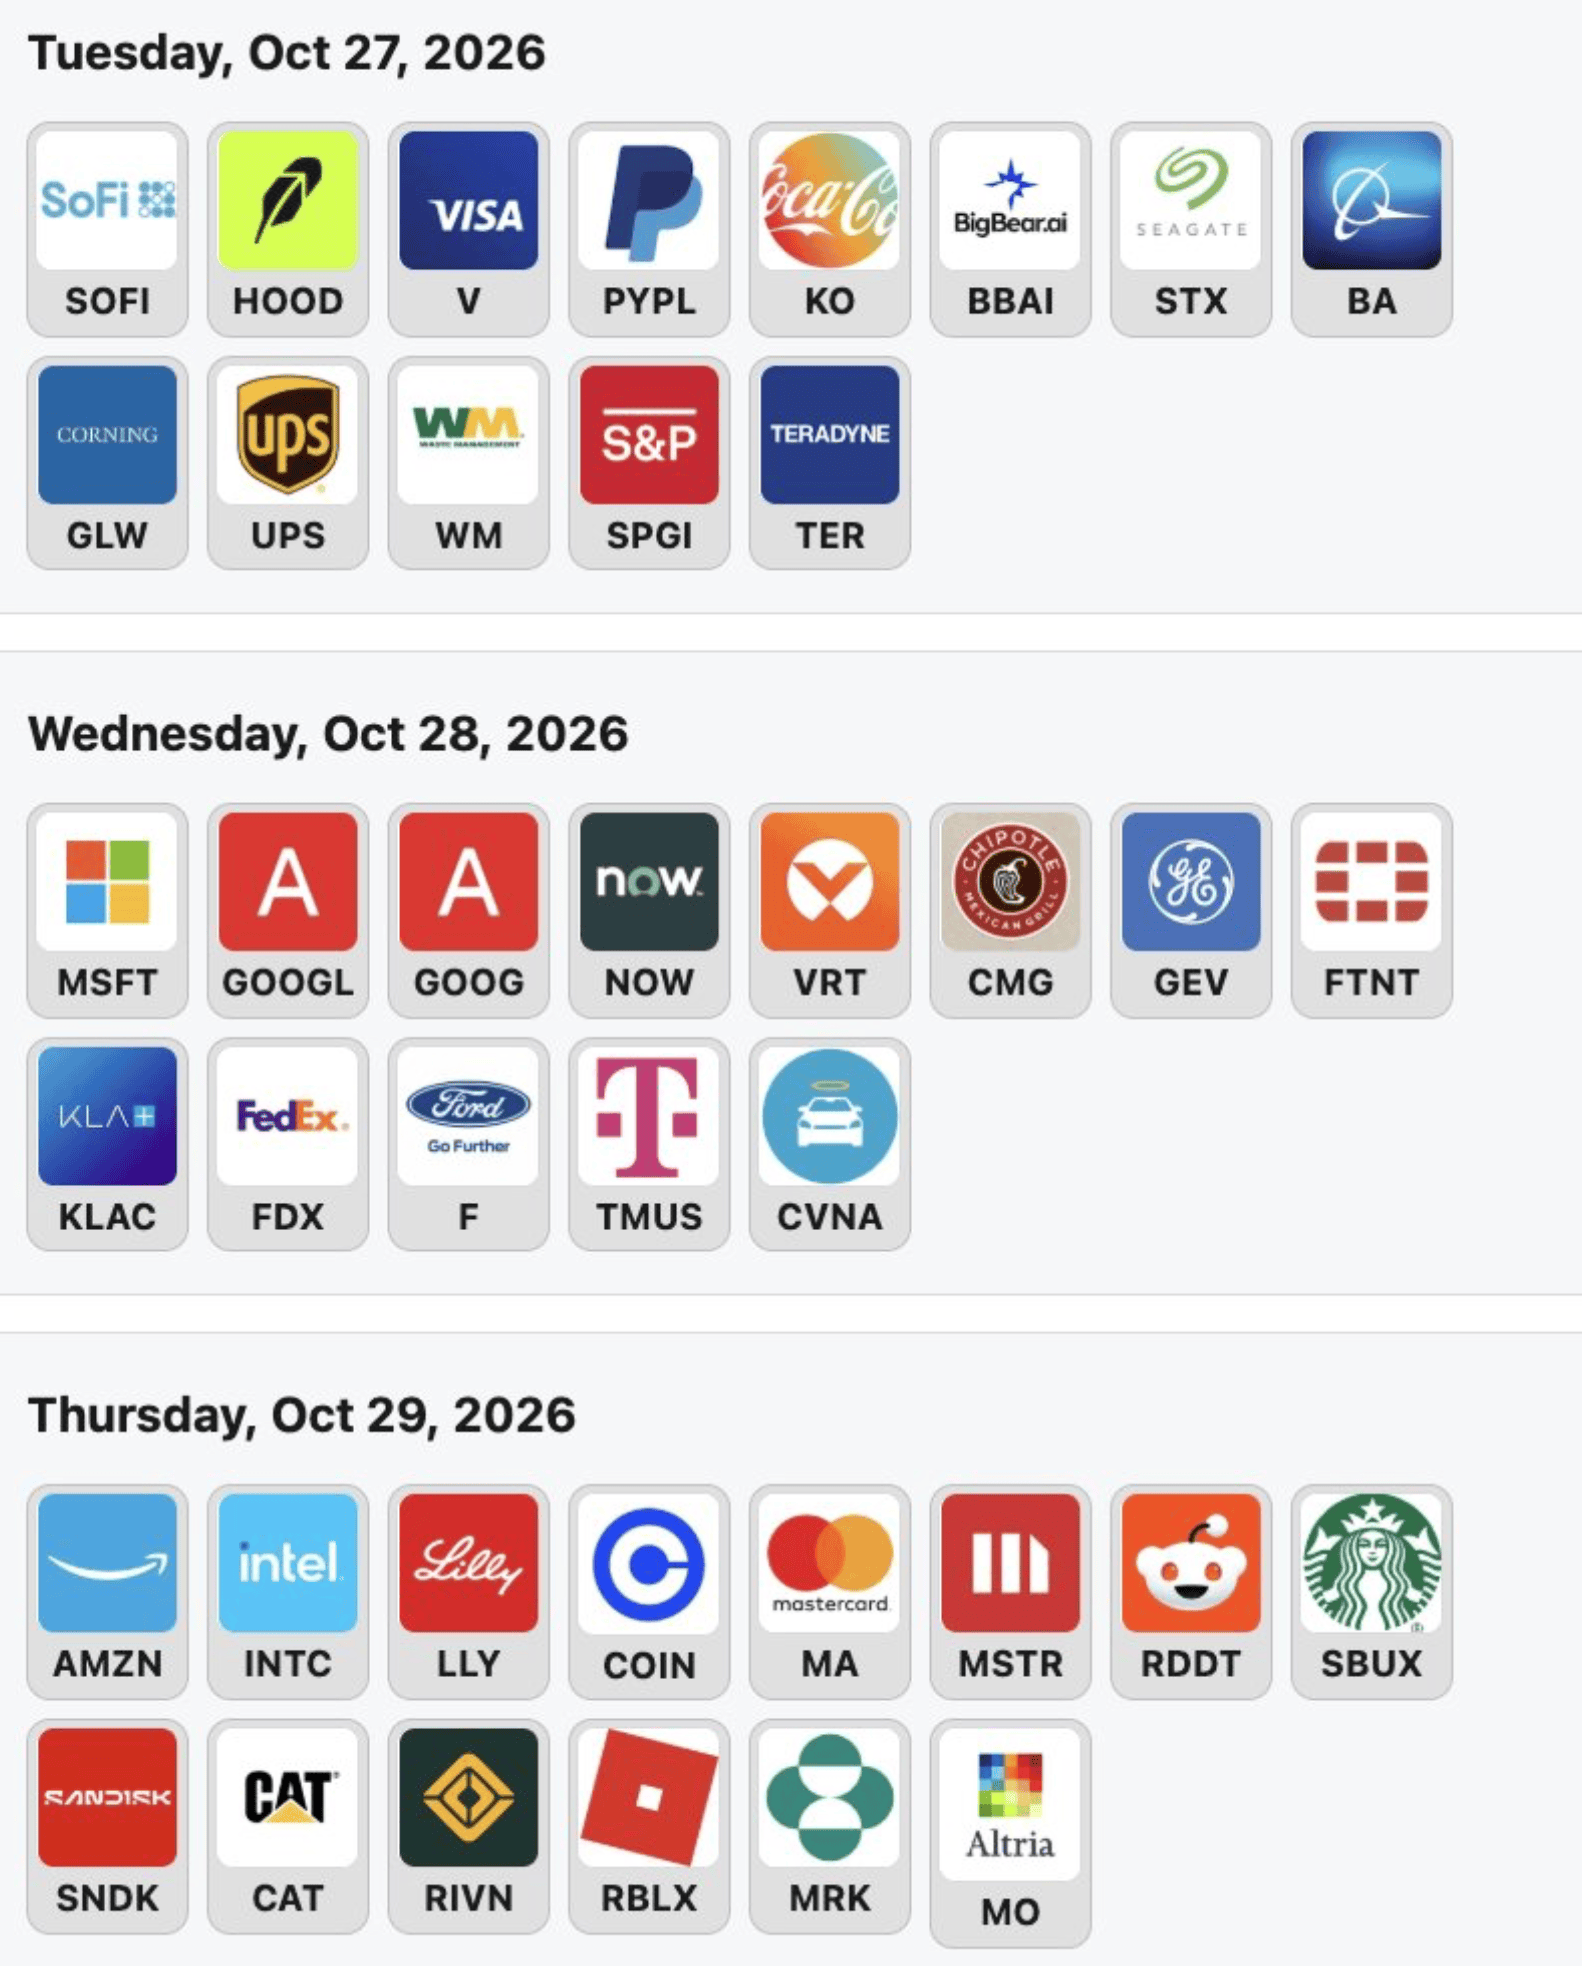
upcoming results
-
I doubt they can afford to do too much(harm) unless you're a bank, like to gamble a lot, maybe drink a lot
-
Do we have Sandisk in the funds
-
Hi- No we do not. The reasons are many
MU is a pure play manufacturer, Sandisk is a joint venture manufacturer (with Kioxia)
MU manufacturers both NAND and DRAM, Sandisk is solely, NAND
MU hold 3X the Nr of current patents
MU is at a scale Sandisk can never match
MU is exposed to markets growing at a faster paceSandisk is a good business, no doubts. I may have mentioned that I did a lot of work on it over 20 years ago when the business was run by Eli Harari and Sanjay Mehrotra (MU
 )
My philosophy is to pick the best of breed within a sector. EG Nvidia over AMD. And whilst AMD has appreciated more in the past year, you are now sitting with AMD on a multiple almost 4X greater(75!) but strangely with half the margins and half the growth. We will see how that plays out. Imo when people talk of bubbles this company is it.

