
Nvidia News
-
Record numbers
Revenue hard to say really however several tail winds. Blackwell yet to peak/firing. Vera Ruben mass production.
Demand exceeds supply
China H200 albeit modest.I think they could report close to $95B. The Guide will be at least +$10B over the reported Nr.
I think the QoQ rhythm is now in the range +$15B. If you go back we predicted $100B quarters by end of 26-early!Margins 75-76%. The transition to Ruben will always see a small initial margin compression due to yield. Corrects back end of the year.
Operating Margin 62%
Net income margin circa 55% (tax paid earnings margin)Nvidia has trailing growth rate of 80% and a realistic fwd of 45-50% over several years.
-
Ignoring any revaluation of investments-operationally we expect the following when Nvidia report fiscal Q2 earnings after the close tonight! Expect Jensen to say Vera Ruben is in full production and demand for it is the highest in their history+ Blackwell has yet to peak.
Our expectations
Revenue $95–96B
Gross margin 75–76%
Operating margin ~65%
Operating income ~$62B
Underlying net income ~$51-53B (EPS $2.12-$2.15) excluding MTM on investments
Q3 revenue guidance $107–108B
In summary:
$95–96B revenue / 75–76% GM / ~65% operating margin / ~$62B operating income / ~$50B underlying net income / $107–108B Q3 guide.
For reference, current market expectations are around $92B for Q2 and $104B for Q3, so this would be a clear beat+raise -
So the naysayers will obviously state that the bubble will burst soon as they only made 62B
-
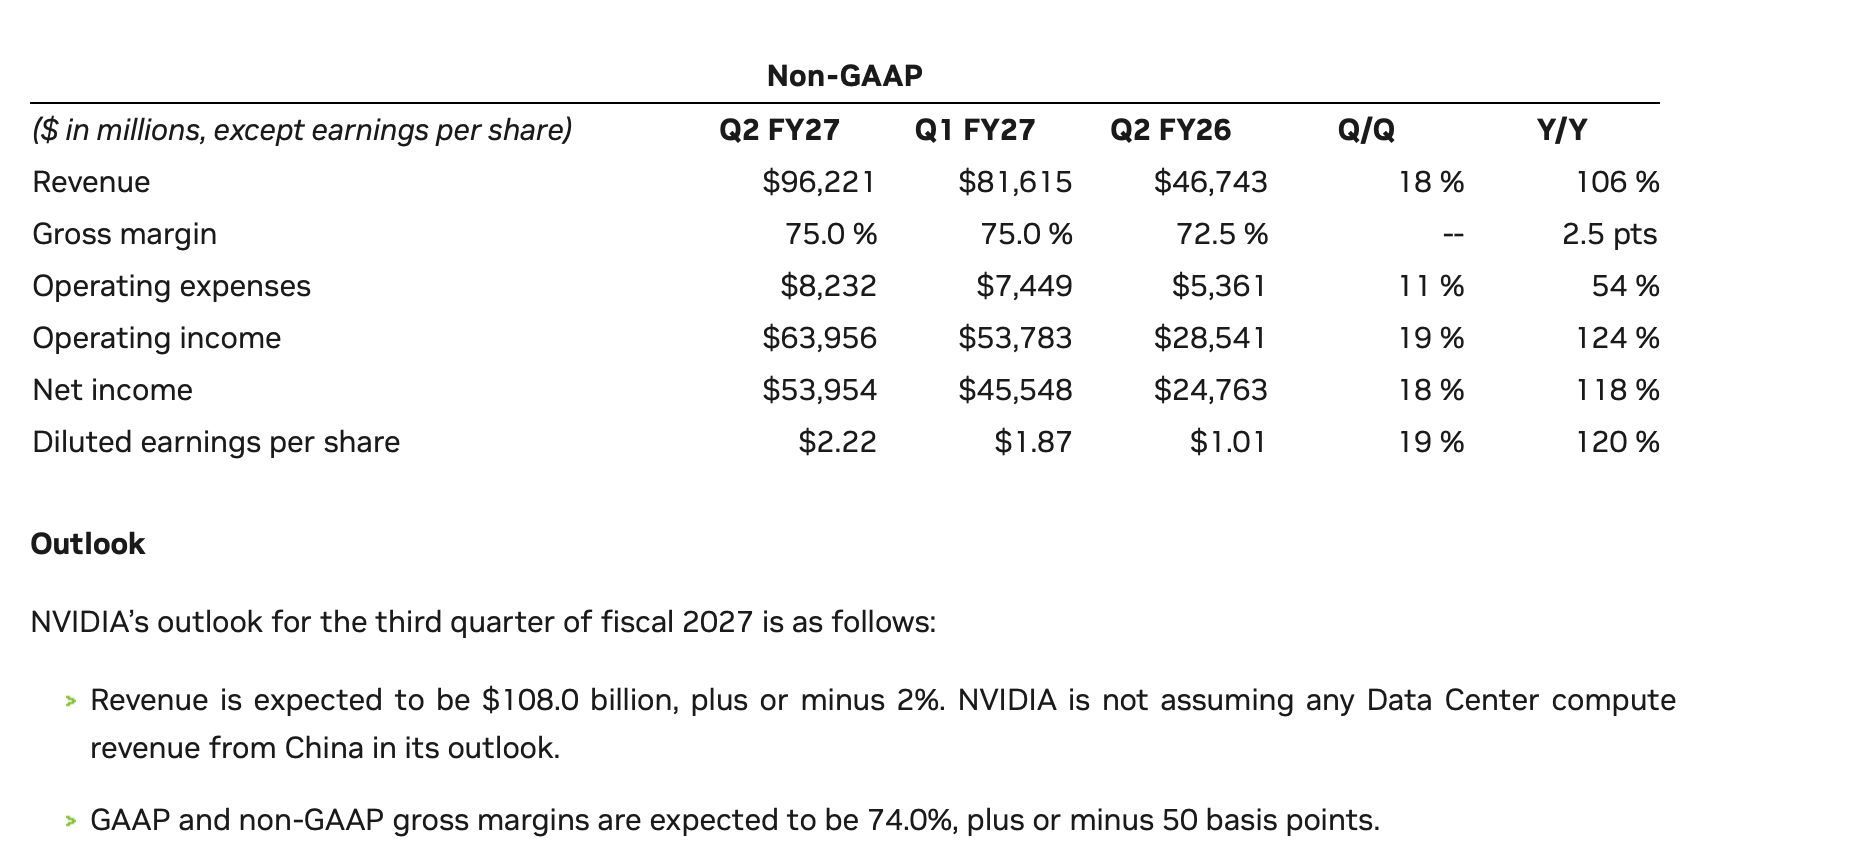
Results are as noted above. 96b revenue. Margin check. Guide, check.
-
Here is the result-it's fantastic and way better than consensus.
Revenue CHECK
GM CHECK
Operating Income 64b (+2)
Net Income 54B-
The guide was $108B CHECK!
100% growth people and a sub 20 multiple.And the icing on the cake. Nvidia said it is facing “extreme” memory costs and supply constraints, which are affecting its gross margins. Reports from the call say Nvidia expects those costs to pressure margins into the next quarter. Micron popped $30 AH. Nvidia $9-$10
Im not concerned about Nvidia margins as they intend raising prices 15% in Jan 27
-
the CFO said they expect 70% revenue growth in fiscal 2028

would be 100% if not constrained. -
NVIDIA–AMAZON: MAJOR EXPANSION OF AI INFRASTRUCTURE DEAL
NVIDIA and Amazon Web Services have dramatically expanded their AI partnership, with AWS committing to deploy an additional 2 million NVIDIA GPUs across its global infrastructure during 2027–28. This is on top of the more than 1 million NVIDIA GPUs already committed by AWS, taking the total deployment to more than 3 million GPUs.
While the financial terms have not been disclosed, a reasonable estimate is that the additional 2 million GPUs could represent $70–100bn or more of hardware, once the GPUs, networking, NVLink, memory and complete NVIDIA systems are included. The overall AWS commitment could therefore ultimately represent well over $100bn of NVIDIA-related infrastructure spending.
Importantly, this is not simply a GPU purchase.The expanded relationship covers NVIDIA's Blackwell Ultra, Rubin and Rubin Ultra platforms, Vera CPUs, networking, software and NVLink, with Amazon also becoming the first collaborator on NVIDIA's next-generation custom high-bandwidth memory technology (custom memory as mentioned by Micron only weeks ago).
For NVIDIA, the announcement provides exceptional visibility into future demand and is another powerful confirmation that hyperscaler AI investment remains enormous. AWS is effectively doubling down on NVIDIA despite continuing to develop its own Trainium chips.
The key takeaway: more than 3 million NVIDIA GPUs committed to AWS, with the incremental commitment alone potentially worth around $100bn once the complete infrastructure stack is included. -
The facts are that Nvidia is increasing its market share across the entire AI infrastructure. So despite 'news' of various competitors and partners developing new XPU/Asics etc, Nvidia is becoming more embedded within the stack. Jensen commented on OpenAi's Jalapeno, saying 'he's pleased for his partners and wishes then every success-we didn't wake up losers'.
If you look at their latest results, their revenue is 10X the size of AMD and almost 30X the net income! Nvidia generate AMDs annual profit in 21 days(and falling). And the bit that most have forgotten, AMD has given away 20% of the entire company to its customers(for zero $) just to get them to buy their product.
Long live the King
-
The Telegraph has just told me that Nvidia is planning an additional $150bn share buyback. I'm also reassured that this is A Good Thing by the same publication.
Will this Good Thing occur in the form of increased share price immediately or a gradual increase in the coming months/years?
In short, while I can understand how this happens, can someone explain the consequences to me using small words?
Thanks!
-
A simplistic worked example .
A company has 1000 shares outstanding
The company generates earnings of $10,000-which equates to $10/share (EPS)The company's treasury department purchases its own stock. It buys its own stock on the open market (because management believes it's undervalued). The stock is trading at at $200/share.
They purchase 25 shares for $200 ($5000) and cancel them.
Shares outstanding are now 1000-25 =975 and using the same earnings of $10k, EPS rise to $10.26
The notion being that a companies stock (per share) is now worth more because the EPS/cashflow, whatever the metric is now greater. Or put another way, less shares sharing the same earnings.
The main take away with buy backs is it's a strong signal that management think(and they are best placed to know) that the stock is undervalued. After all the primary objective of management re capital allocation is to achieve the best return for shareholders.
-
Thanks Adam. Hugely helpful, as always.
I'm guessing therefore that this big signal of management confidence will lead to a share price rise as people view the company more confidently, as well as the higher future EPS (as per your explanation).
So A Good Thing indeed!
-
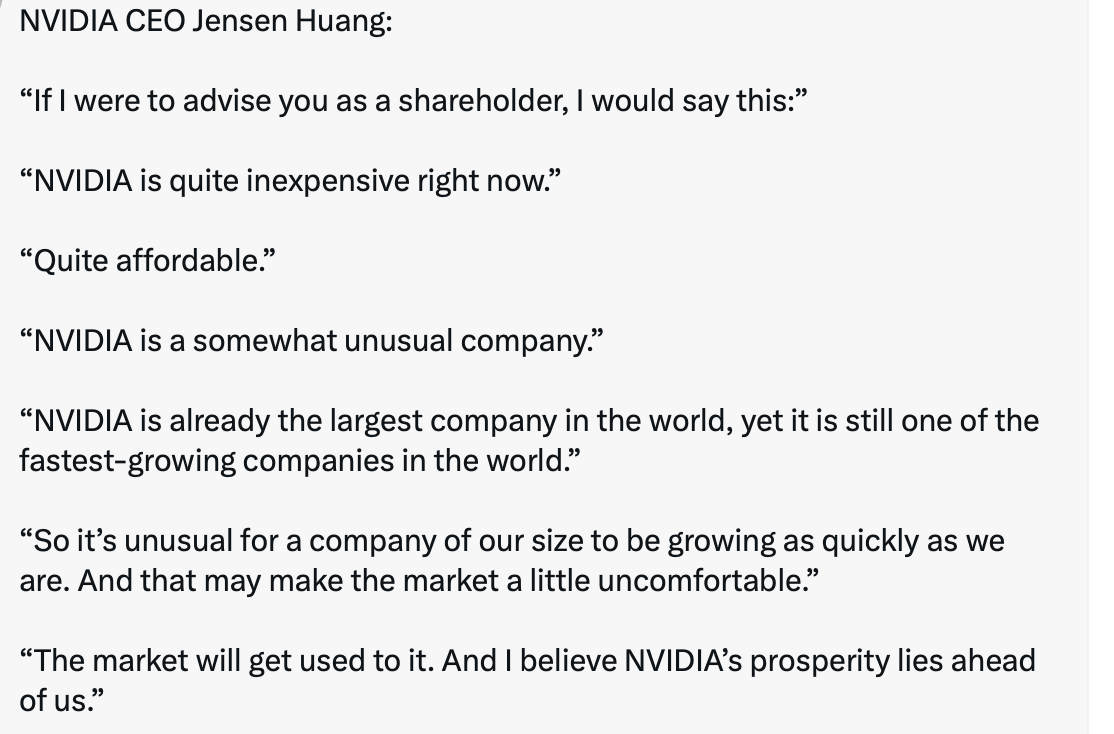
The main overhang for Nvidia stock is it's now the most valuable company in existence. This clearly weighs of the minds of investors so I believe it is a psychological issue albeit temporary in the grand scheme of things. If you step back and look at the numbers, their PE, cashflow, ROI, take your pick is about 2X(better) than it was 2 years ago. Granted its valuation was 'full' back then when PE's were 50! We had price to sales of 25X.
The market seems to forget material information only to 'remember' when certain things are repeated or come to fruition. Management stated only weeks ago that revenue in 2027 will be $750B+ and you can take 50% of that straight to the bottom line. Here is a giant, growing at 50% per annum with a multiple in the teens. Granted it won't maintain that beyond a few short years but imo there arent many if any other businesses that offer such compelling ratios, risk vs reward, growth with low relative multiples and very important, durability. Apple for example trades at twice the multiple whilst having 1/3rd the growth. Im not suggesting Apple is over valued-it mimics a bond more than equity due to its elite credit worthiness(equal to govt debt in fact).
-
right on cue. Jensen Huang said this yesterday. Very similar narrative to the above
-
At risk of explaining egg-sucking to grandmas:
Another thing that I have seen over my years in tech (cough, now retired, of course) are share splits.Again, & in general, often a sign of a company doing well: share price has been rocketing, for example, to $200 a share. They split - the number of shares doubles, but the price halves: no material difference in the market cap of the company, BUT perhaps the share price can continue an upward trajectory - happy days.
In my personal case, on joining a company, I was advised to join ASAP, because within a week, a share split was scheduled to happen. Made quite a material difference to our later situation, even though at the time I really didn't understand it

Of course, a company in trouble might split the other way -

Adam, you are absolutely right that the Nvidia price is a psychological issue.
Many of us struggle to accept that the upward trajectories of several companies can continue without some event. Some youtube experts continuously predict the next market crash....yet here we are.My view is to take some gains from time to time. A wise head once suggested when things are on an upward path, take perhaps 10% a year to cash: invest it, spend it, but remove it from the vagaries of the market. Of course there are times when hindsight clearly makes that the wrong decision, but sometimes it works, & some of this is "peace of mind".
For us, I like to keep a 'proportion' of our net worth in cash, or cash-like assets (eg, premium bonds, savings accts) - around 10%. If things get out of kilter, that is what I try to gently rebalance. Rightly or wrongly!