
Broadcom (AVGO)
-
I keep a close eye on growth (and margin). There is no point investing in companies with falling growth, tempered with the fact as numbers get very large you can't keep growing at the same pace. However PEG is a critical metric for a mature business. I'd never pay over 2. A decade ago the gold standard was 1.0 and today the experts would have you believe anything less than 2 is a good proposition-i strongly disagree.
Palantir has a PEG of 4-5 and it's interesting that their management and many analysts will point to high growth, high margins etc. But Nividia beats it on all those key metrics and yet has a PEG of 0.5. So if anyone wonders how this comes about, I don't blame you because it makes no sense to me either. We don't hold the stock and won't, for precisely this reason. It's a good business but imo its valuation is obscene. As expected it's gone nowhere, in fact those that purchased mid 2025 are flat, which is exactly what happens at extreme valuations. And if management made just one misstep the stock will be cut in half.
I say this purely to articulate that valuation always needs a sense check, never get caught up in FOMO, there are some simple numbers anyone can look at to get a rough guide on relative value. And investing is all about risk and return. A stock with a very frothy valuation can certainly move much higher but when you buy it you are taking on much more risk relative to the gains you might make.
-
Breaking
Broadcom announced agreements with Google and Anthropic, today and are shaping up to be some of the most significant AI infrastructure deals in the industry. The long-term contract with Google runs through 2031 and covers the development and supply of future-generation tensor processing units (TPUs) as well as networking and other components for next-generation AI racks.
While the company has not disclosed financial terms, the scale and strategic nature of the deal suggest it could generate tens of billions of dollars in revenue over the next decade.
In parallel, the agreement with Anthropic gives the AI chatbot company access to approximately 3.5 gigawatts of TPU compute capacity starting in 2027. Industry estimates for the cost of building and operating TPU-scale AI hardware indicate that this portion alone could represent multi-billion to potentially tens of billions USD in infrastructure investment.Combined, the two deals could plausibly exceed $50 billion USD, making them a transformative, multi-year revenue driver for Broadcom and cementing its role in the rapidly expanding AI hardware market.
-
When the 'news'(fake) dropped I was highly sceptical...also the rumour Nvidia was buying DELL-makes no sense at all. DELL is a low margin capital intensive business -the exact opposite environment that Nvidia operates in.
JPM says reports that MRVL won Google TPU business are false, arguing Google is talking to multiple parties while AVGO remains the clear incumbent.
-
News out-a good example of how based on evidence, Broadcom had the wind at its back

Apple (AAPL) has signed a new multi-year agreement with Broadcom (AVGO) worth more than US$30bn, marking its largest commitment under its American Manufacturing Programme.
The deal will see Broadcom produce more than 15bn US-made chips through 2031, expand its Fort Collins, Colorado facility with a US$1.5bn investment, and support hundreds of American jobs. The company will supply custom silicon, including advanced RF components and wireless connectivity technologies for future Apple products. -
A fantastic Broadcom result. Look at the growth. Couple with a current multiple of 30 and a 1 year fwd of sub 20. The guide is for growth to accelerate to 90%+
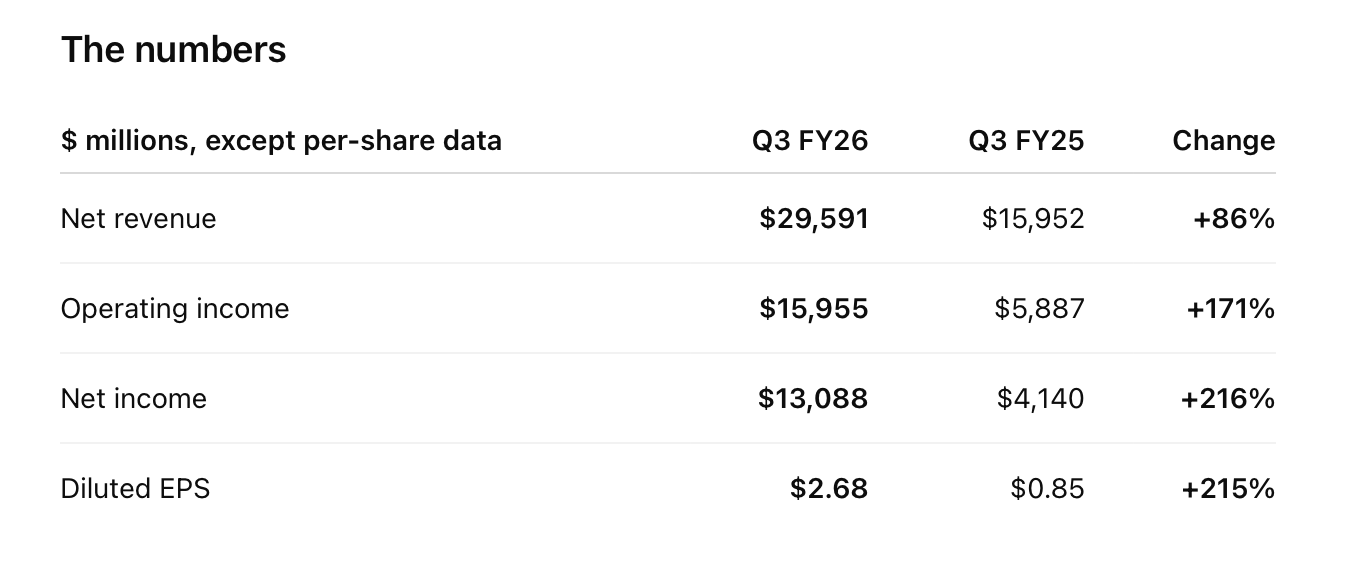
The earnings growth is even more striking than the revenue growth. GAAP net income more than tripled to $13.1 billion.
AI is becoming the story
Broadcom's semiconductor business generated $20.8 billion of revenue in Q3, up 127% year on year.
AI semiconductor revenue alone was $16.7 billion, meaning AI accounted for roughly 80% of semiconductor revenue during the quarter.
More importantly, AI revenue increased 54% sequentially. Broadcom is therefore not simply benefiting from a strong year-on-year comparison — the business is accelerating quarter by quarter.And the Q4 outlook suggests that acceleration is continuing:
Q3 AI semiconductor revenue: $16.7bn
Q4 expected AI semiconductor revenue: $21.7bn
That is approximately $5 billion of additional AI revenue in a single quarter.Cash generation remains exceptional
Q3 FY26 Q3 FY25 Change
Cash flow from operations $14,197 $7,166 +98%Broadcom generated $13.7 billion of free cash flow in the quarter, equivalent to approximately 46% of revenue.
The company ended the quarter with $24.0 billion of cash and cash equivalents, up from $19.6 billion at the end of the previous quarter.The mix is shifting rapidly towards semiconductors. Semiconductor Solutions now represents 70% of total revenue, compared with 57% a year ago, with AI responsible for the overwhelming majority of the growth.
Q4 outlook
Broadcom expects Q4 revenue of approximately $34.8 billion, up 93% year on year.
That would represent another $5.2 billion of revenue growth sequentially, taking quarterly revenue to a level more than double that of Q4 last year.
The most important number, however, is the AI forecast:
AI semiconductor revenue: $21.7 billion, up 236% year on year.
The message from Broadcom is therefore very clear: AI demand is not merely remaining strong — it is accelerating.
Investor takeaway
This is a very difficult set of numbers to argue with.
Revenue: +86%
GAAP operating income: +171%
GAAP net income: +216%
GAAP EPS: +215%
AI semiconductor revenue: +221%
AI semiconductor revenue sequential growth: +54%
Free cash flow: $13.7 billion
Q4 revenue guidance: +93% year on year
Q4 AI semiconductor guidance: +236% year on year
The critical question for investors is no longer whether Broadcom is participating in the AI infrastructure build-out. It clearly is.
The question is how long this extraordinary rate of AI spending can continue — and how large Broadcom's share of that spending can become. -
And further comments relating to the AI segment which note, was a 'mere' 16.7B last Q
"Based on all this -- on this Q4 guidance, I should say, we expect our fiscal 2026 AI revenue to be $58 billion, for the year, up 186% year-upon-year and above our prior guidance of $56B." (President, CEO Tan)
"In 2027, we have secured the supply to again double AI revenue to approximately $115 billion. "In 2028, we have line of sight for fiscal 2028 AI semiconductor revenue growth to again double to $230 billion." (President, CEO & Executive Director Tan) "We are very much on target to exceed $30 in earnings per share in fiscal 2028."