General News
-
The Orange One has been given a bloody nose in the midterms; midterms always do that to sitting presidents but this seems a bit more messy than they normally are.
What impact does this have on investments? Any at all? (I notice that things looked a bit rosier yesterday after a bad end to last week, but the IM funds only moved a smidge today. Maybe there is more to come.)
-
Hi O,
I wouldn't read too much into the midterms from an investment perspective. Historically, markets have generally performed well in the 12 months following midterm elections, irrespective of which party controls Congress.
A weakened Trump administration could actually be positive for markets, particularly if it reduces the scope for further disruptive policy decisions. Political gridlock is not necessarily a bad thing for investors.
Ultimately, corporate earnings, interest rates and economic growth will determine market direction, not the election results. In particular, the structural growth in AI and associated infrastructure spending is unlikely to be materially affected.
The facts remain that over the last 2 quarters the earnings and guidance of our holdings have hit records whilst prices have moved sideways. Multiples are at historical lows too. It's a disconnect which always corrects.
-
Foxconn: AI demand continues to surge — November 2026
Foxconn, one of Nvidia's principal AI server manufacturing partners, has reported exceptional growth and expects AI-related operations to expand further in Q4.- October revenue: $39.7 billion, up 46% year on year, setting an all-time monthly record.
- First 10 months of 2026: Approximately $280 billion in revenue, up 40.4% year on year.
- AI servers: Strong demand for Nvidia systems continues to support manufacturing activity and expansion.
- Q4 outlook: Foxconn expects further growth in AI-related operations, alongside seasonal strength in consumer electronics.
- US expansion: Foxconn is expanding its AI server manufacturing footprint in Houston, Texas.
Further management comments
Foxconn's chairman, Young Liu, also made several notably bullish statements on 30 October:- No AI bubble: Liu explicitly rejected concerns that AI infrastructure investment is a bubble.
- 2027 growth: Foxconn expects another year of double-digit growth.
- AI server shipments: Management expects AI rack shipments to more than double in 2026.
- Longer-term demand: Foxconn previously indicated that AI production capacity demand should remain very strong in 2027.
- OpenAI: A further collaboration is being developed, potentially extending its role in AI infrastructure.
Reuters:
Foxconn is reporting record revenue, forecasting continued AI growth into 2027 and expanding production capacity. For Micron, the read-through is strongly positive for memory volumes, although Foxconn has not explicitly forecast DRAM shortages or higher memory prices.
-
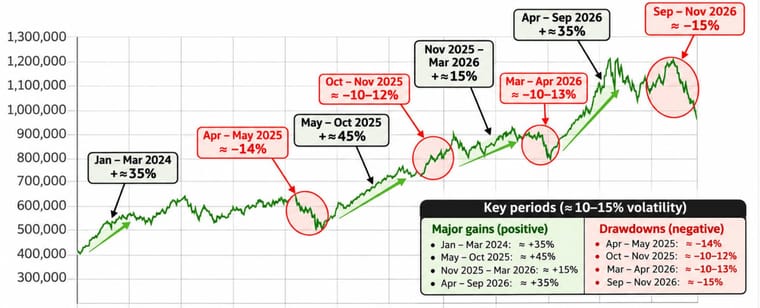
Good periods and not so good periods-what is important is there has been no structural destruction in the fundamentals of these holdings(Technology).
-
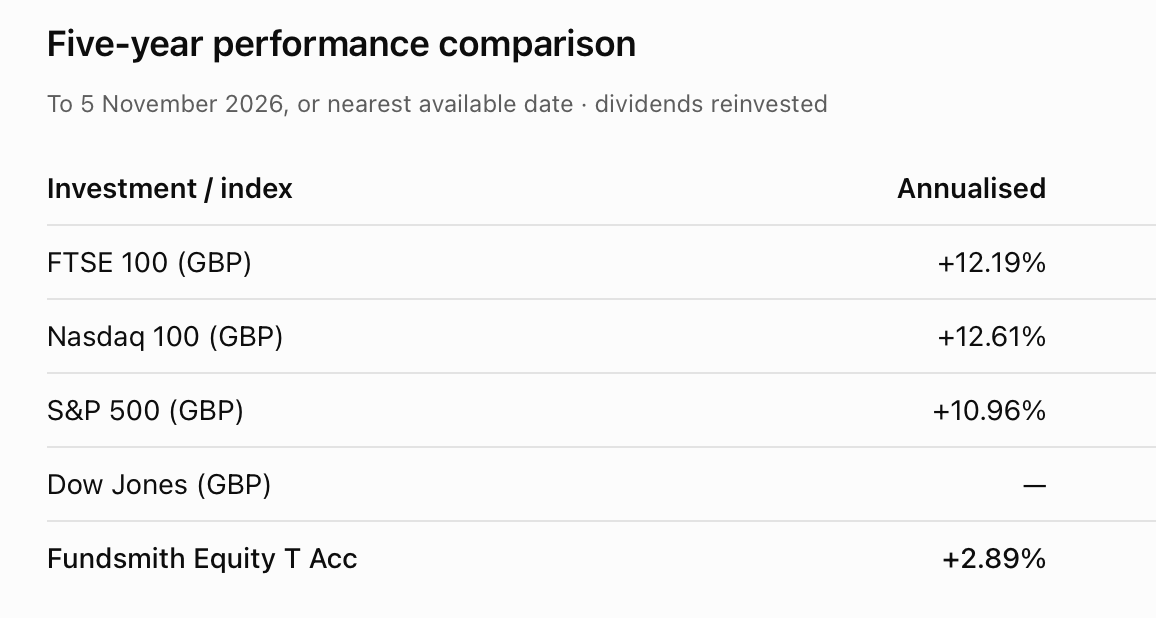
That graph looks good - I don't know what the units are but it's up from 400,000 in Jan to 950,000 now (so more than doubled in less than a year.) Can't complain about that. However I looked up the numbers for my portfolio just now and it's not pretty .... I guess it's a matter of riding the lows and looking ahead to the future highs, with confidence they will arrive. It's perhaps ironic that Fundsmith (boo! hiss!) hit an ATH yesterday.
Thanks for keeping us updated Adam.
-
Ouch ….
Just had a look ….numbers not pretty ..but there was a time when I was very happy with its current value…you’ve spoilt us Adam.. -
-
Interesting comments from Goldman Sachs CEO David Solomon, echoing exactly what I've been arguing about Democratic opposition to US data centre construction.
The demand for AI compute isn't going to disappear simply because politicians decide to make building data centres more difficult. The investment will simply move to states or countries that actually want it, taking jobs, capital and economic growth with it.
Solomon makes precisely this point, warning that the infrastructure will naturally move outside the US because the demand for compute is there.
He also confirms that financing demand for AI infrastructure remains very strong, with Goldman heavily involved in capital markets transactions.
For Nvidia and Micron, this is an important distinction. A data centre built elsewhere still needs GPUs, HBM and DRAM. Political obstruction may delay orders, but it doesn't magically eliminate the underlying demand.
The irony is that politicians claiming to protect American interests could end up exporting one of America's greatest economic opportunities.
Markets seem increasingly determined to confuse temporary obstacles with structural problems. They're not remotely the same thing.
-
A summary of Morgan Stanley Research
Morgan Stanley (8 November 2026): Buy the Drop – AI Investment Opportunities Following the US Midterms
Morgan Stanley believes the recent AI-related market sell-off is unwarranted and an overreaction to the US midterm election results. Its central argument is that AI investment isn't being cancelled; some data centre construction is simply being pushed into 2029.
The numbers are quite extraordinary.
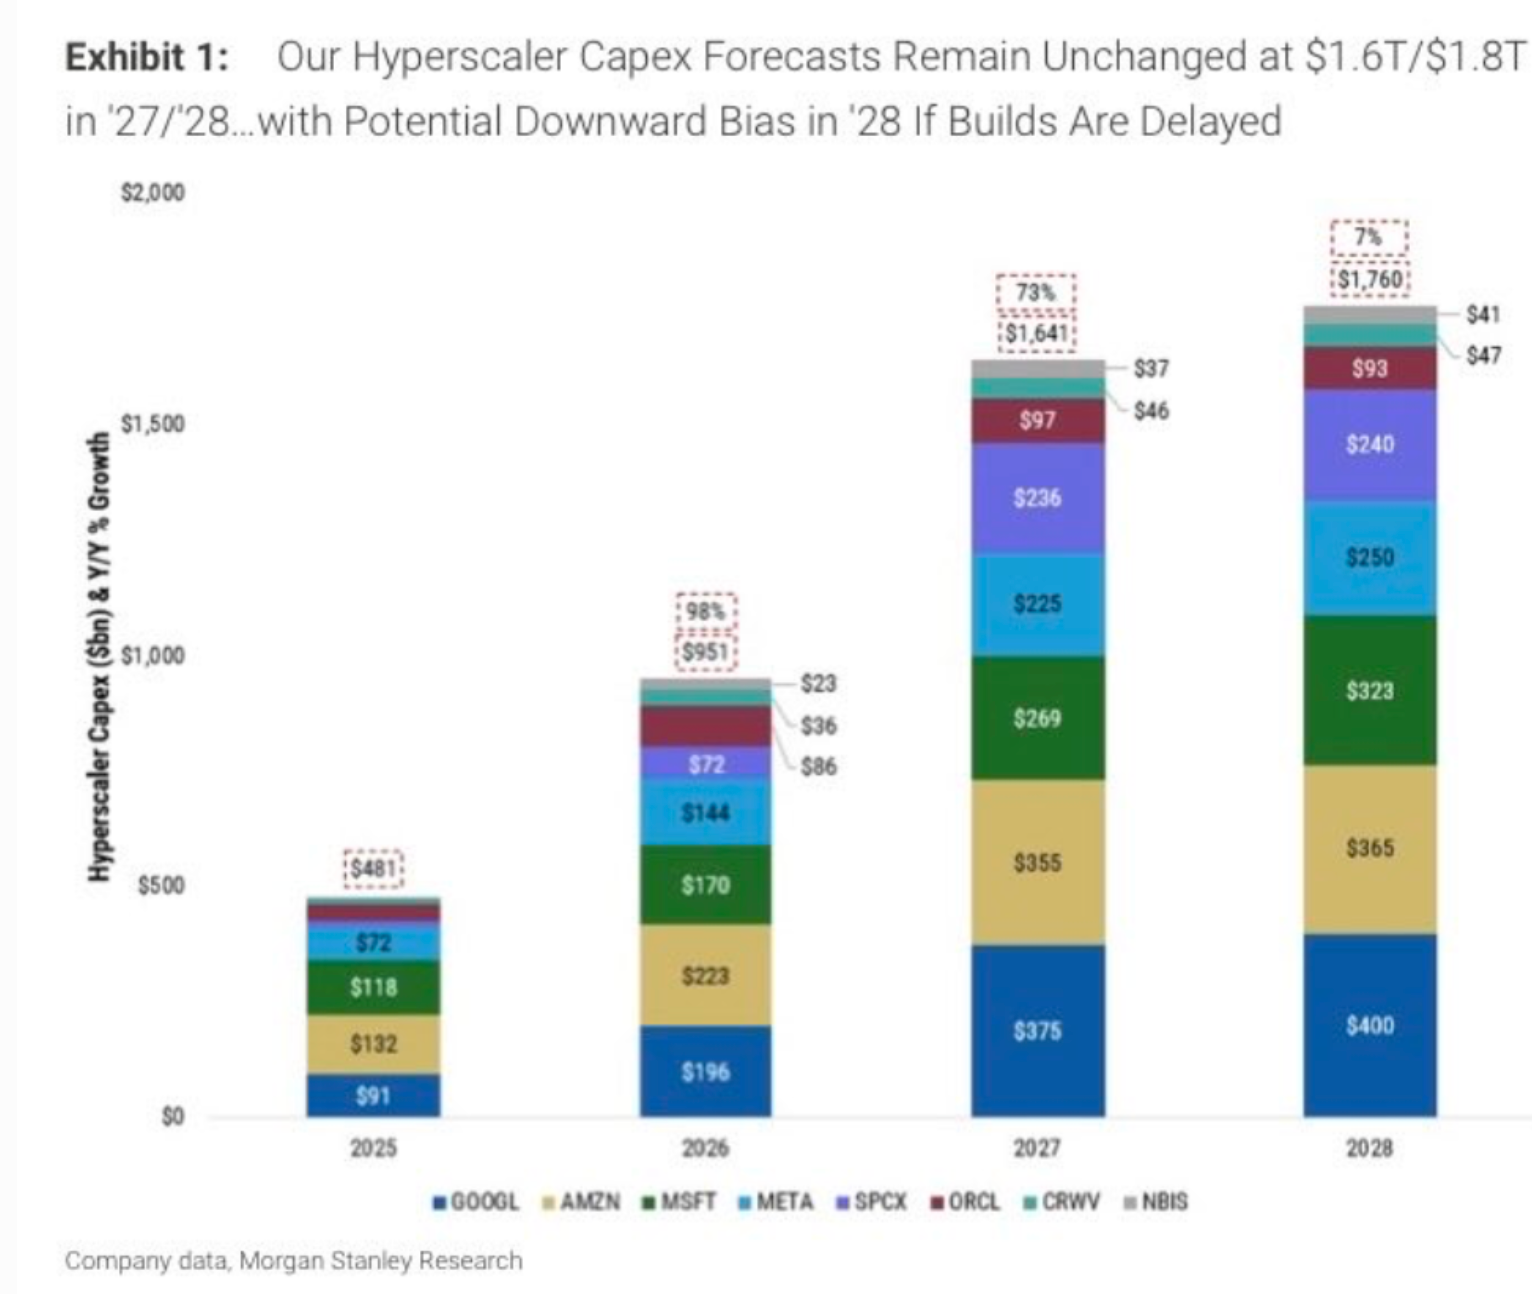
Morgan Stanley's hyperscaler capital expenditure forecasts remain unchanged:
2025: $481bn
2026: $951bn (+98%)
2027: $1.64 trillion (+73%)
2028: $1.76 trillion (+7%)
That's approximately $3.4 trillion of investment in 2027–28 alone, with Google, Amazon, Microsoft and Meta accounting for the overwhelming majority.
Morgan Stanley expects approximately 20% of planned US data centre projects for 2028, representing 5GW of capacity, to shift into 2029 following political and regulatory changes. Importantly, that's only around 10% of global projects, and 2027 construction forecasts remain unchanged.
Its modelling suggests global data centre capacity additions will still grow 9% in 2028 and 20% in 2029. US additions are expected to decline 4% in 2028 before rebounding 38% in 2029.
Morgan Stanley also forecasts a greater than 30% shortfall in powered data centre capacity through 2028. In other words, demand for compute infrastructure continues to exceed available supply.
There are several important implications.
First, the AI investment cycle could actually last longer. Delaying some projects rather than cancelling them potentially extends the spending cycle, improves supply-demand balance and supports pricing for existing compute capacity.
Second, the largest technology companies benefit. Google, Amazon, Microsoft and Meta have the financial resources, infrastructure and flexibility to navigate regulatory delays, higher construction costs and power constraints. Smaller developers and heavily leveraged operators face greater challenges.
Third, compute efficiency becomes increasingly important. Meta is targeting a tenfold improvement in compute efficiency during 2027, while Google is delivering substantial improvements through its TPU hardware and software. More efficient models should make AI applications commercially viable across a much broader range of products and users.
Fourth, there are risks. Morgan Stanley acknowledges that a slowdown in 2028 construction could temporarily weaken pricing power, increase inventories and pressure margins across parts of the technology supply chain. It also warns that further delays could create downside risk to its 2028 capex forecast.
Nevertheless, the bank remains constructive on hyperscalers, selected semiconductor companies, AI infrastructure and software businesses, arguing that recent share-price weakness presents buying opportunities.
My takeaway: This is hardly the collapse of the AI investment cycle that some commentators have been predicting. Morgan Stanley is forecasting almost $3.4 trillion of hyperscaler investment over just two years, with compute demand continuing to exceed available capacity.
There may be some disruption to the timing of projects, particularly in 2028, but the underlying investment thesis remains firmly intact.
For companies supplying the essential computing and memory infrastructure, including NVIDIA and Micron, that is a substantially more encouraging outlook than recent market sentiment would suggest.