
Microsoft
-
-
Microsoft’s $6.2 B, five-year agreement with Nscale Global and Aker to rent hyperscale AI infrastructure in Norway, underscores its aggressive push to scale AI capabilities. Announced today, the deal grants Microsoft access to high-performance AI compute capacity starting in 2026, leveraging Norway’s abundant renewable energy and stable regulatory environment. Nscale Global, a British data centre firm, and Aker, a Norwegian investment company, will deliver infrastructure tailored for AI workloads, which demand advanced cooling and high power density. Norway has an abundance of cheap hydro power and it's naturally cold

This move aligns with Microsoft’s $80 billion AI infrastructure investment through 2028, prioritising speed and flexibility over building new facilities. By leasing rather than constructing, Microsoft reduces capital costs and accelerates deployment, complementing its Azure expansion. The deal also reflects a strategic shift toward partnerships, mitigating risks in a dynamic AI market where hardware evolves rapidly, ensuring Microsoft remains competitive in cloud and AI services.
-
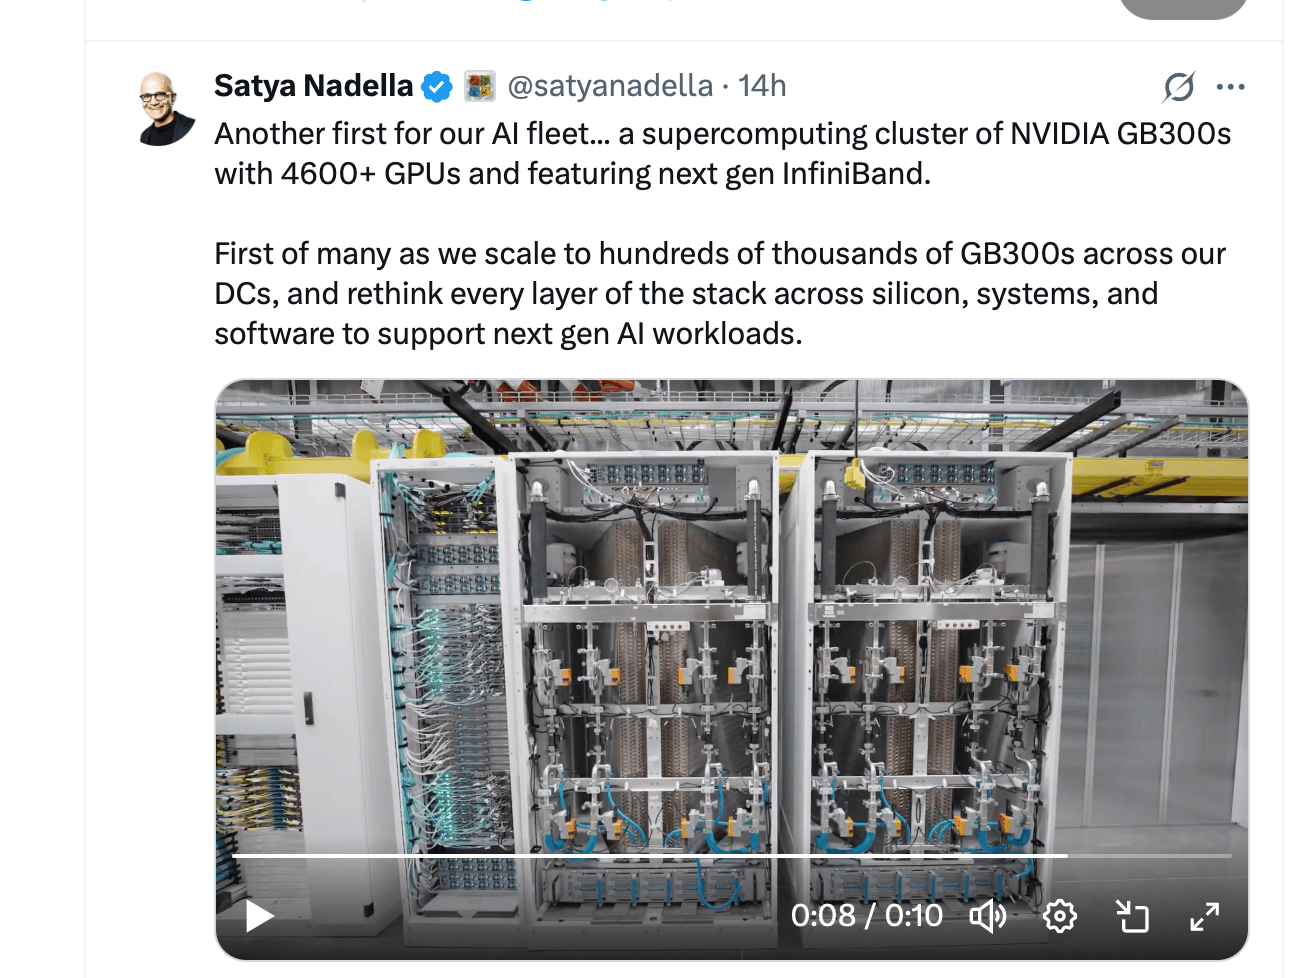
MSFT deploy their first Blackwell Ultra cluster. A mere 65 racks. Several hundred thousands additional GPUs coming.
-
Msft received multiple analyst upgrades last night prompting a pop to $550(+$20) in pre market. All eyes on tomorrow's earnings. It should be very strong.
MSFT and Apple might join the 4T club today!
-
MSFT signed an agreement with OpenAI valuing its stake at roughly $135 billion. Microsoft said it supports OpenAI’s move to form a public benefit corporation (PBC) and undertake recapitalisation.
Following the deal, Microsoft holds an investment representing around 27% of OpenAI Group PBC on an as-converted diluted basis, including employees, investors, and the OpenAI Foundation. Excluding recent funding rounds, Microsoft’s earlier stake was 32.5%.
OpenAI has also agreed to purchase $250 billion in Azure services, though Microsoft will no longer have exclusive rights to supply computing power. The partnership maintains Microsoft as OpenAI’s primary model collaborator, with exclusive intellectual property and Azure API rights until artificial general intelligence (AGI) is achieved.
Microsoft’s IP rights extend through 2032, excluding OpenAI’s consumer hardware, while OpenAI gains flexibility to collaborate with third parties. -
A very strong MSFT result- the softness AH is yet again concern over AI spending-odd given the Nr's are great.
Microsoft reported its fiscal Q2 2026 results (quarter ended 31 December 2025) on 28 January 2026, after market close. The company delivered strong top- and bottom-line growth, driven primarily by its cloud and AI businesses, beating analyst expectations across key metrics. However, shares dropped around 6-7% in after-hours trading, reflecting investor concerns over escalating capital expenditure (capex), slightly moderating cloud growth rates, and margin pressures from AI investments.Key Financial Metrics with ComparativesHere is a table summarising the main figures, including year-over-year (YoY) changes, constant currency (CC) adjustments, and comparisons to analyst consensus estimates.Metric
Key Financial Metrics
Revenue: $81.3 billion (+17% YoY, +15% constant currency)
Operating Income: $38.3 billion (+21% YoY, +19% constant currency)
Net Income (GAAP): $38.5 billion (+60% YoY)
Net Income (Non-GAAP): $30.9 billion (+23% YoY, +21% constant currency)
EPS (GAAP): $5.16 (+60% YoY)
EPS (Non-GAAP): $4.14 (+24% YoY, +21% constant currency)
Microsoft Cloud Revenue: $51.5 billion (+26% YoY, +24% constant currency) — first time over $50 billion
Capex: $37.5 billion (+66% YoY)
Shareholder Returns: $12.7 billion (+32% YoY)Segment RevenueProductivity and Business Processes: $34.1 billion (+16% YoY, +14% constant currency)
Intelligent Cloud: $32.9 billion (+29% YoY, +28% constant currency)Azure and other cloud services: +39% YoY (+38% constant currency)More Personal Computing: $14.3 billion (-3% YoY)
Other HighlightsCommercial Remaining Performance Obligation (RPO): $625 billion (up significantly YoY)
Q3 FY2026 Guidance: Revenue $80.65–81.75 billion (15–17% growth); Azure growth 37–38% constant currencySegment BreakdownProductivity and Business Processes: $34.1 billion revenue (+16% YoY, +14% CC). Microsoft 365 Commercial cloud +17%, Consumer +29%, Dynamics 365 +19%, LinkedIn +11%. Solid demand for AI-integrated tools like Copilot.
Intelligent Cloud: $32.9 billion revenue (+29% YoY, +28% CC). Azure and other cloud services +39% (+38% CC), beating estimates. Commercial remaining performance obligation surged to $625 billion (up massively), indicating huge future backlog. This segment was the standout, fuelled by AI demand.
More Personal Computing: Revenue declined, dragged by Gaming (Xbox content/services down, hardware weakness) and other areas, though Windows OEM and search advertising showed some resilience.Guidance and OutlookQ3 FY2026 revenue:
$80.65-81.75 billion (midpoint $81.2 billion, in line with estimates).
Azure growth: 37-38% (CC), slightly below Q2's 39% and some higher expectations.
Overall revenue growth guided at 15-17%.
No major changes to full-year outlook, but continued emphasis on heavy AI investments. CFO Amy Hood noted capex will stay elevated to meet demand.Main Points and CommentaryMicrosoft absolutely blew it away on the headline numbers—consistent beats on revenue and EPS, with five straight quarters of surprises now.
Azure's 39% growth highlights leadership in the AI race, cloud revenue crossed $50 billion for the first time, and metrics like the surging performance obligations signal explosive long-term potential. **CEO Satya Nadella stressed accelerating AI adoption, with strong uptake in Copilot tools.**That said, the after-hours drop (to around $430-450 range from a close near $480) —it's a market reaction to near-term pressures in an already high-valuation AI story. Key triggers:Ballooning Capex: $37.5 billion (well above estimates) raises fears of an "AI tax" where infrastructure spending (data centres, GPUs) outpaces near-term monetisation. Investors question ROI timelines, especially with potential for $100 billion+ annual spend.
Cloud Growth: Azure's 39% was strong but a slight slowdown from prior acceleration, and Q3 guidance of 37-38% came in light for some. Capacity constraints were acknowledged as persisting.
Margin and Segment Weakness: Lighter margin outlook due to AI costs, plus drags from gaming and personal computing, shifted focus to risks over beats.
High Expectations: With the stock at a premium valuation, any hint of "not perfect" sparks sell-offs amid broader AI hype cooling.Overall, this looks like a classic overreaction and potential buy-the-dip—fundamentals are rock-solid, and AI demand isn't vanishing. Short-term volatility may linger until clearer signs of ROI from those investments emerge, but Microsoft has a history of conservative guidance proving beatable.
-
Microsoft (MSFT) is broadening its AI-driven consumer health services with the launch of Copilot Health, which integrates data from a variety of sources—including wearable devices, health records, and lab test results—to deliver what it terms “medical intelligence.”
The company sees this feature as a step towards “medical superintelligence,” defined by Microsoft as “health AI that can ultimately combine the broad knowledge of a general practitioner with the specialised expertise of a specialist.”Copilot Health will be rolled out gradually, initially in English in the U.S. for users aged 18 and over. Those wishing to gain early access can join a waitlist.
It collects information such as activity levels, sleep patterns, and vital signs from over 50 wearable devices, including Fitbit, Oura, and Apple (AAPL) Health. It can also integrate health records, including visit summaries, medication lists, and test results, from more than 50,000 U.S. hospitals and providers via HealthEx. Lab results from Function can also be incorporated. -
It's a great business albeit not that exciting-safe and durable. Their scale and reach opens them up to finding something to complain about-at the end of the day they are a business, they have millions of customers. Some won't be happy customers. Apple gets a lot of flack from some too. Ive always found them a pleasure to deal with. In saying that ive never had a piece of expensive hardware fail prematurely and tried to get some goodwill but I have dealt with their support relating to products many years outside warranty(without Apple Care) and always found them helpful.
-
Microsoft's Earnings: AI Spending Is Delivering Exceptional Growth
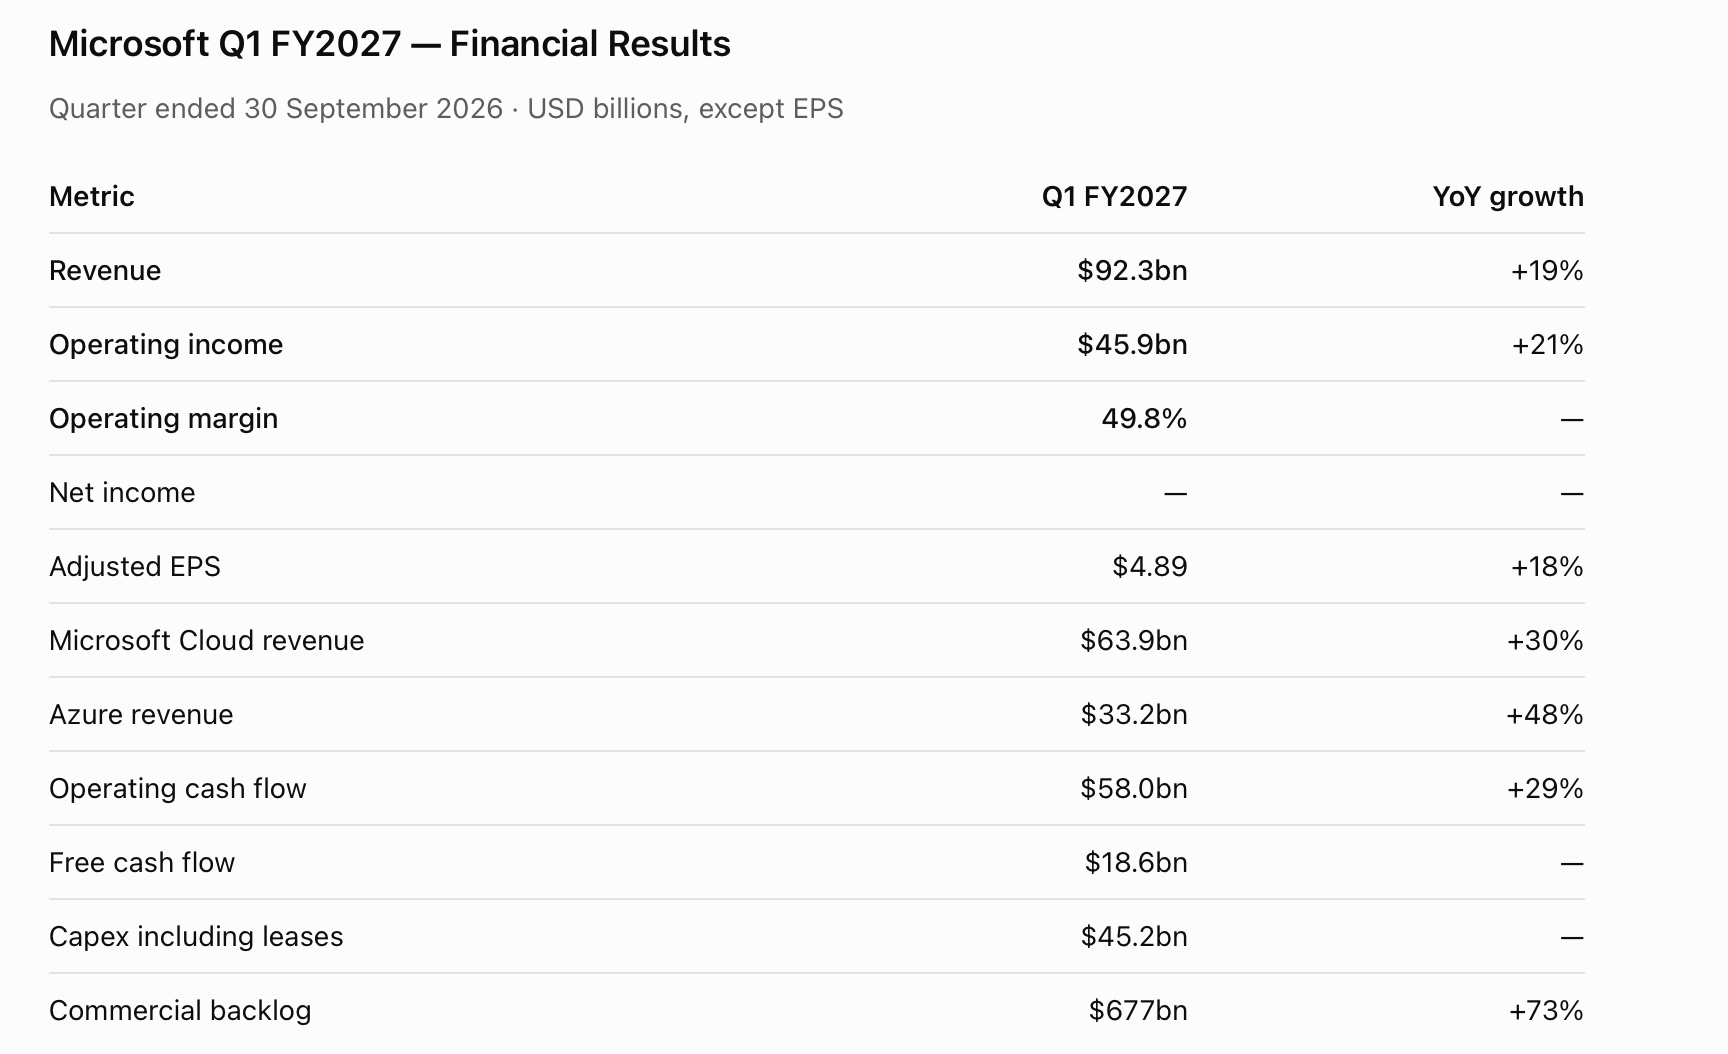
Microsoft delivered another outstanding quarter, comfortably beating expectations on revenue, earnings and Azure growth, demonstrating that the AI infrastructure investment cycle is translating into substantial commercial returns.
Q1 FY2027 revenue increased 19% to $92.3 billion, while operating profit rose 21% to $45.9 billion, representing an exceptional operating margin of nearly 50%. Adjusted EPS reached $4.89, up 18%.
Azure was the standout performer, with revenue surging 48% year-on-year to $33.2 billion. Microsoft Cloud revenue reached $63.9 billion, growing 30%.
Perhaps most impressive is Microsoft's $677 billion commercial backlog, up 73%, providing extraordinary forward revenue visibility as contracted demand converts into recognised revenue.
Microsoft generated $58 billion in quarterly operating cash flow and $18.6 billion in free cash flow, despite investing heavily in AI infrastructure.
Capital expenditure, including leases, reached $45.2 billion, with spending expected to exceed $50 billion next quarter. Azure growth is forecast to accelerate further to 49–50%.
The key takeaway: Microsoft is simultaneously delivering accelerating AI demand, exceptional profitability and enormous contracted future revenue.
For NVIDIA, Micron and the wider AI infrastructure supply chain, Microsoft's continued investment represents another powerful confirmation of sustained demand.